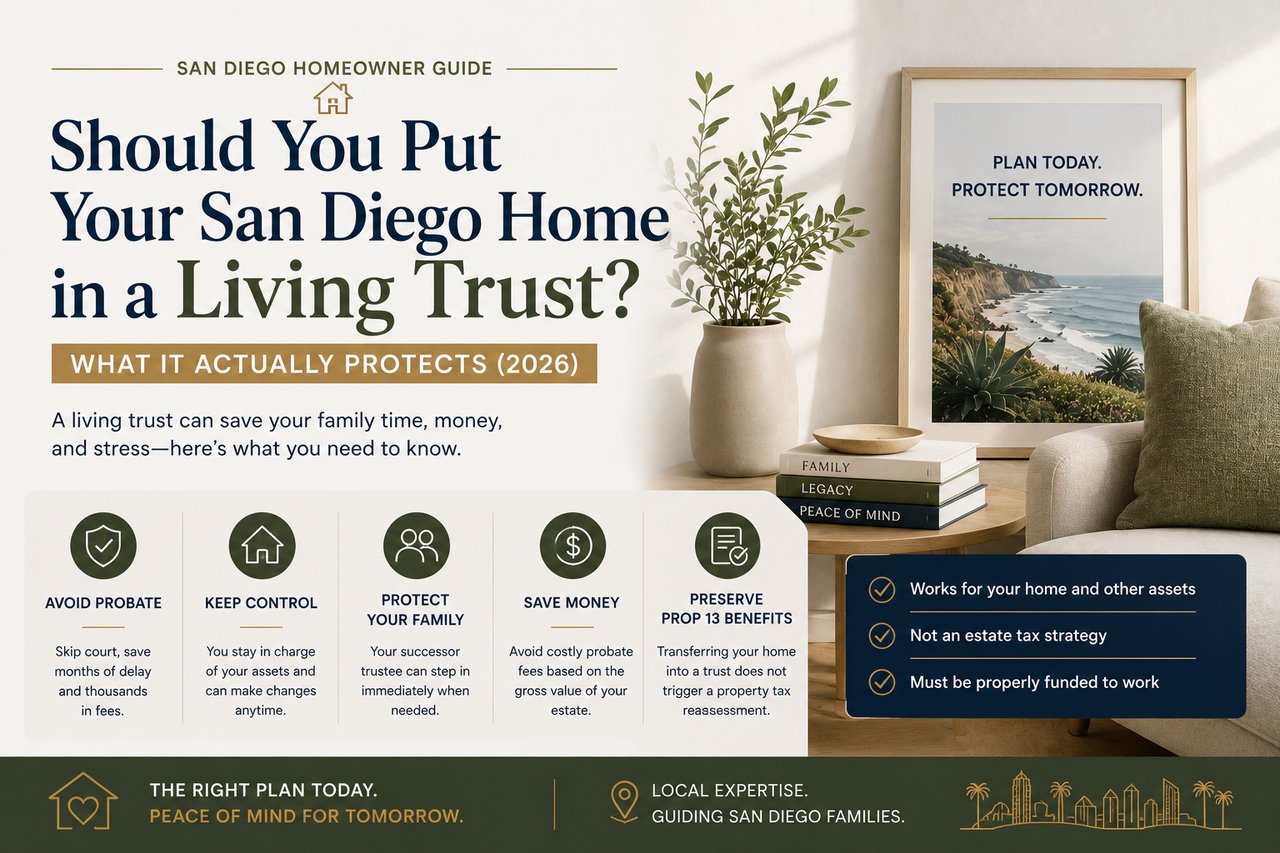
Should You Put Your San Diego Home in a Living Trust? What It Actually Protects (2026)
Most San Diego homeowners have heard they should "probably get a trust," usually from a friend, an attorney's ad, or an estate planning seminar, without a clear sense of what it actually does. That vagueness matters, because a living trust is genuinely one of the most useful tools available to California homeowners, but only if you understand the specific problem it solves and the specific mistakes that quietly undo it. Here's what a revocable living trust actually accomplishes for someone who owns real property in San Diego, what it doesn't do, and what it costs to set one up correctly.
What a revocable living trust actually is
A revocable living trust is a legal entity you create during your lifetime to hold title to your assets, most importantly your home. While you're alive, you're typically the trustee, meaning you keep full control over everything in it, and you can sell, refinance, or change the trust's terms whenever you want, which is exactly what makes it "revocable." You also name a successor trustee, someone who automatically steps into your role if you become incapacitated or when you die, without needing a court to appoint anyone. That last part is the whole point. When you die, the trust simply continues under your successor trustee's control, who can then sell the home, distribute it to your beneficiaries, or manage it exactly as your trust document instructs, with no court involvement required.
The main thing it does: skip probate entirely
If you've read anything about what happens to a San Diego home without a trust, you already know the alternative isn't pleasant. Probate here typically runs 9 to 18 months for a straightforward estate, sometimes considerably longer, on a court calendar that handled over 2,300 estate and trust filings in the most recent fiscal year alone. A revocable living trust sidesteps that timeline completely, since trust assets never enter probate in the first place.
The cost side is where this really lands for San Diego homeowners specifically. California sets probate attorney and executor fees by statute, and both the attorney and the personal representative are separately entitled to the same percentage-based fee: 4 percent of the first $100,000 of the estate's gross value, 3 percent of the next $100,000, 2 percent of the next $800,000, and 1 percent of the next $9 million. Critically, this is calculated on gross value, meaning your mortgage balance doesn't reduce the number the fee is based on. Run that math against San Diego's countywide detached home median of $1,074,000, and you get roughly $23,740 in statutory fees on the attorney side alone, and the same amount again for the executor, for a combined total pushing $47,000, on a single median-priced home with no other complications. A living trust avoids that entirely, which is a big part of why it's become the default recommendation for basically anyone who owns real property in a market with San Diego's home values.
Funding the trust doesn't trigger a reassessment, but you actually have to do it
Under California Revenue and Taxation Code Section 62(d), transferring your home into a revocable living trust where you remain the present beneficiary isn't considered a change in ownership, so it doesn't trigger a Prop 13 reassessment. Your existing assessed value carries over into the trust untouched. This is the same reassessment framework that governs everything else in the Prop 13 and Prop 19 system, and here it works in the homeowner's favor: setting up a trust costs you nothing on the property tax side.
The catch is that this protection only applies to homes actually transferred into the trust, and this is where a huge number of California trusts quietly fail. Signing a trust document creates the entity, but it doesn't move your house into it. That requires a separate step: recording a new deed that transfers title from you individually to yourself as trustee of the trust. Plenty of people pay an attorney to draft a beautiful trust document, sign it, file it in a drawer, and never record the deed that actually funds it with their home. If that happens, the house is still titled in your individual name when you die, which means it still goes through probate regardless of how well-drafted the trust itself is. An unfunded trust is one of the most common and most expensive estate planning mistakes out there, precisely because it looks like the job is done when it isn't.
What it doesn't do
A revocable living trust isn't an estate tax strategy, and for the overwhelming majority of San Diego homeowners, it doesn't need to be. Recent federal legislation set the estate tax exemption at $15 million per individual starting in 2026, made permanent with no scheduled sunset, meaning a married couple can pass roughly $30 million tax-free. Even San Diego's most expensive coastal properties rarely put a typical family estate anywhere near that threshold, so estate tax avoidance simply isn't the problem a trust is solving here.
It also doesn't protect your assets from your own creditors while you're alive, since a revocable trust is fully within your control, and courts generally treat assets you can revoke and reclaim at will as reachable by your creditors just as if you owned them directly. It doesn't replace the need for a will either. Most trust packages include what's called a pour-over will, which catches any asset you forgot to formally transfer into the trust and directs it there after death, but that asset still has to go through probate to get there if it wasn't already funded correctly. And a trust doesn't change anything about how Prop 19 treats your home once it passes to your kids. The one-year move-in requirement and the current exclusion cap on inherited property apply exactly the same way whether the home passes through a trust or through probate. A trust changes the process your heirs go through, not the property tax outcome they end up with.
Trust versus will, in plain terms
People often treat these as competing options, but a trust and a will do different jobs, and most complete estate plans include both. A will only takes effect after you die and only after a probate court validates it, which is exactly the process a trust is designed to avoid. A trust takes effect the moment you fund it and continues operating seamlessly through incapacity and death without court involvement. The pour-over will that typically accompanies a trust exists purely as a backstop, catching anything you didn't get around to formally retitling into the trust before you died, and directing it there, though that asset still has to pass through probate first since it wasn't in the trust to begin with. If your goal is avoiding probate on your home, the trust is the document doing that work, not the will.
Choosing a successor trustee
The successor trustee is the person who steps in to manage or distribute the trust when you can't, whether due to incapacity or death, and this choice matters more than people initially treat it. It doesn't have to be your oldest child or your spouse by default; it should be whoever is genuinely organized enough to handle financial and legal responsibilities, and willing to do so fairly if there's more than one beneficiary involved. Many people name a spouse first, an adult child or trusted family member second, and a professional fiduciary or trust company as a third-tier backup if no individual is available or willing. Naming a backup for your backup is worth doing up front, since it's a lot easier to address on paper now than to sort out later if your first choice can't serve when the time comes.
What it costs, and why the math usually favors it
An attorney-drafted revocable living trust in California typically runs $1,500 to $3,000 for a straightforward estate, with attorneys generally billing $200 to $400 an hour if they're not working on a flat fee. More complex estates, multiple properties, blended families, or specific tax planning needs can push the cost to $5,000 or more. On top of the drafting fee, expect notarization costs around $15 per signature and deed recording fees of roughly $50 to $200 per property to actually fund the trust. Even at the higher end of that range, the total cost is a small fraction of the roughly $20,000 to $50,000 or more in statutory probate fees a San Diego-priced estate would otherwise generate, which is the core reason attorneys here recommend trusts so consistently.
What this means if you own a home in San Diego
Get the trust drafted by someone familiar with California real property rules, then treat funding it as a separate, non-optional step rather than an afterthought. That means actually recording a new deed transferring your home from your individual name into the trust, and confirming with your attorney or the title company that the Prop 13 exclusion paperwork is filed correctly so the transfer doesn't accidentally trigger a reassessment. Once it's funded, keep the trust updated as your life changes, a refinance, a new property, a change in who you'd want as successor trustee, since an outdated trust can create the same kind of confusion an unfunded one does.
What this means if you're set to inherit through a trust
A trust means the person managing the estate can distribute or sell the home without waiting on a probate court, which is a real and meaningful advantage in terms of time and cost. But don't assume it changes anything about the tax side. If you're planning to keep the home, the same Prop 19 one-year move-in deadline and exclusion cap apply whether the transfer happens through a trust or through probate, and the same capital gains step-up basis rules apply too. A trust gets you to the finish line faster and cheaper. It doesn't change where that finish line is on the tax side.
Figuring out whether this makes sense for your situation
The math on a living trust is specific to what you own, how it's titled, and how your family situation might change over time, but for most San Diego homeowners, the probate costs alone make this one of the more straightforward decisions in estate planning. If you want help thinking through whether a trust makes sense for your property, or you're not sure whether an existing trust was actually funded correctly, reach out and we'll go through what you have and what might be missing.
Disclaimer
I'm not a trust or estate planning attorney, and nothing in this article is legal advice. Trust structures, funding requirements, and tax treatment are specific to your situation and can change with the law, so talk to a licensed California estate planning attorney before setting up, funding, or relying on a trust.