Your Tax Return Says You Can't Afford a House. Your Bank Account Disagrees (2026)
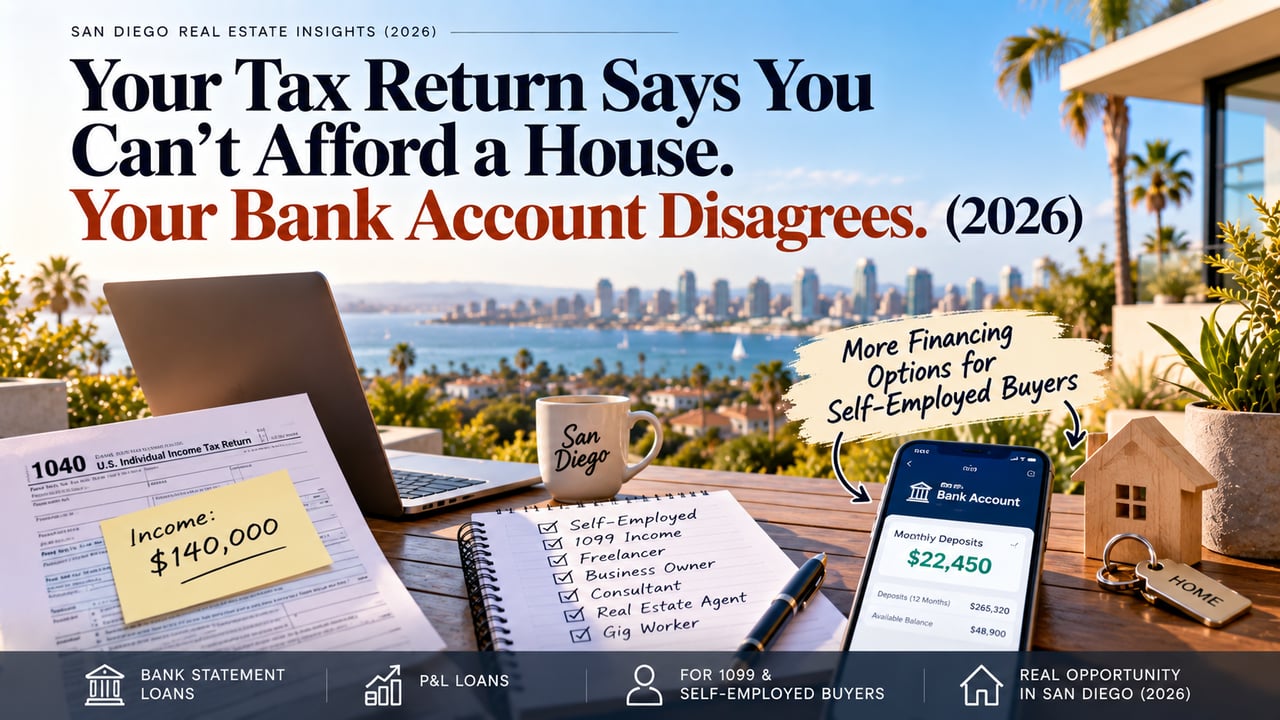
San Diego has no shortage of people who earn a genuinely comfortable living without ever collecting a W-2: freelance consultants, rideshare and delivery drivers, real estate agents, tradespeople running their own small operations, military veterans who left the service to start a business, and a long list of independent contractors who invoice clients instead of clocking in. More than one in ten California workers are primarily self-employed, and a lot of them run into the exact same wall when they try to buy a home. Their tax return, built around every legitimate deduction their accountant could find, makes their income look too thin to qualify for a mortgage, even when their actual bank balance tells a completely different story. The good news is that mortgage financing has genuinely caught up to this problem, and the options available in 2026 are better and more mainstream than they were even a few years ago.
Why a strong earner can look weak on paper
A traditional mortgage lender starts with a borrower's tax returns and works backward from net income, the number left over after every business expense, deduction, and write-off has been subtracted out. That's exactly the number a good accountant has spent years working to minimize, which creates a strange mismatch at the worst possible moment. A contractor who nets $140,000 after deductions might have actually brought in $220,000 before running it through a tax strategy built to lower their IRS bill, and a conventional lender using standard debt-to-income math is going to size a mortgage around the smaller number, not the larger one. The borrower did nothing wrong, their tax preparer did their job well, but the mortgage approval ends up punishing exactly the kind of smart tax planning that independent contractors are supposed to do.
Bank statement loans: qualifying off cash flow instead of tax returns
The most established alternative is the bank statement loan, a non-qualified mortgage, or non-QM, product that looks at what actually moved through a borrower's bank accounts rather than what showed up on a 1040. Most programs want 12 to 24 months of personal or business bank statements, and a lender averages the deposits over that period to estimate real cash flow, which tends to land much closer to what a self-employed borrower actually lives on than their adjusted gross income does. Typical 2026 requirements run a minimum credit score somewhere between 620 and 680, with the best pricing reserved for borrowers at 700 and above, a minimum down payment around 10 percent, and three to twelve months of reserves in the bank depending on loan size. Debt-to-income ratios can run as high as 50 to 55 percent on these programs, well above what a conventional loan typically allows, which matters a lot for a borrower whose real cash flow supports a bigger payment than a standard DTI calculation would ever show.
None of this comes free. Bank statement loans carry a rate premium over conventional financing, typically running three-quarters of a point to two and a half points higher, though that gap narrows considerably for a borrower with strong credit, a meaningful down payment, and a full two years of documentation. On the strongest files, 740-plus credit, 25 percent down, solid reserves, the spread over a conventional rate can compress to as little as half a point. A lot of borrowers treat this as a bridge rather than a permanent arrangement, using a bank statement loan to get into a home now and refinancing into conventional financing within a year or two once enough tax returns reflect the income a lender is comfortable using directly.
P&L loans: an option built for the write-off-heavy borrower specifically
A newer and, for some borrowers, more generous option is the profit and loss statement loan, commonly shortened to a P&L loan. Instead of averaging bank deposits, this program qualifies a borrower off a CPA-prepared profit and loss statement covering 12 or 24 months, with no tax returns and, on many programs, no bank statements required at all beyond a couple of months to confirm reserves. The P&L has to come from a licensed CPA, a certified tax preparer, or an IRS-enrolled agent, not something the borrower draws up themselves, which keeps the program from becoming a rubber stamp while still sidestepping the tax-return problem entirely. For a business owner whose tax strategy is specifically designed to minimize reported income, a P&L loan can sometimes produce a higher usable qualifying income figure than even a bank statement loan does, since it's built around the business's actual profitability rather than cash movement through a personal account. Requirements track closely with bank statement programs: a 620 to 680 minimum credit score, 10 to 20 percent down depending on loan-to-value, two years of self-employment history, and three to twelve months of reserves.
These aren't fringe products anymore
It's worth being direct about something that used to be true and mostly isn't anymore: non-QM financing used to carry a certain stigma, a sense that anyone using it couldn't qualify any other way. That's an outdated read on where this market actually sits in 2026. A meaningful share of self-employed and 1099 borrowers, including plenty with excellent credit and substantial reserves, simply have income documentation that doesn't map cleanly onto conventional underwriting, and a growing number of established lenders now offer bank statement and P&L programs as a mainstream part of their regular product lineup rather than a last resort. The products exist because the labor market changed, not because borrower quality dropped.
What this looks like for a San Diego borrower specifically
San Diego's independent contractor population runs wider than the stereotypical gig worker picture. It includes real estate agents working on commission, military veterans who transitioned into consulting or trades after leaving the service, tourism and hospitality workers running their own small operations, and a large freelance and creative economy clustered around the county's tech and biotech scenes. Any of these borrowers can run into the same tax-return mismatch, and San Diego's home prices make the stakes of that mismatch higher than they would be in a cheaper market, since even a modest gap between reported and real income can be the difference between qualifying for a starter condo and qualifying for very little at all. A borrower in this position is usually better served working with a loan officer who actively originates non-QM products regularly, rather than someone who only occasionally touches one, since the underwriting nuances on these programs reward real familiarity.
The documentation still has to be real
None of these programs are a way around actually having the income. A bank statement loan still requires deposits that genuinely reflect business revenue, and a lender will typically back out large, irregular deposits that look more like a loan or a gift than ongoing income. A P&L loan still requires a real CPA willing to put their name on the numbers, and that CPA is vouching for a reasonably accurate picture of the business, not just writing whatever number gets a client approved. Borrowers who've kept clean books, separated business and personal accounts, and worked with the same accountant for a few years tend to move through these programs a lot more smoothly than someone trying to assemble documentation from scratch the month before they want to make an offer.
What this means if you're a self-employed buyer in San Diego right now
Start by talking to a lender who actively originates bank statement and P&L loans before assuming your tax-return income is the ceiling on what you can qualify for, since the gap between what you report and what you actually earn might be exactly the kind of situation these programs were built for. Get your books in order well before you plan to shop for a home, since 12 to 24 months of clean, explainable statements or a CPA-prepared P&L is the foundation these programs are built on, and scrambling to produce that documentation at the last minute rarely goes smoothly.
What this means if you're selling to a self-employed buyer
If a buyer's preapproval letter comes from a non-QM lender rather than a conventional one, that's not automatically a weaker offer, and treating it that way can cost you a legitimate, well-qualified buyer. Ask your agent to confirm the lender's track record closing these specific loan types on time, since the underwriting timeline on bank statement and P&L loans can run a little longer than a standard conventional file, but a well-prepared non-QM buyer is often just as solid as one coming through traditional financing.
The bottom line
The mismatch between what a self-employed San Diego worker actually earns and what their tax return says they earn has a real, mainstream financing answer in 2026, whether that's a bank statement loan built around real cash flow or a P&L loan built around a CPA-verified profit and loss statement. Neither option is free, both carry a modest rate premium and real down payment and reserve requirements, but both exist specifically because conventional underwriting was never built with the modern independent contractor in mind. If you're self-employed and want help figuring out which of these programs actually fits your income picture, reach out and we'll go through the real numbers together.