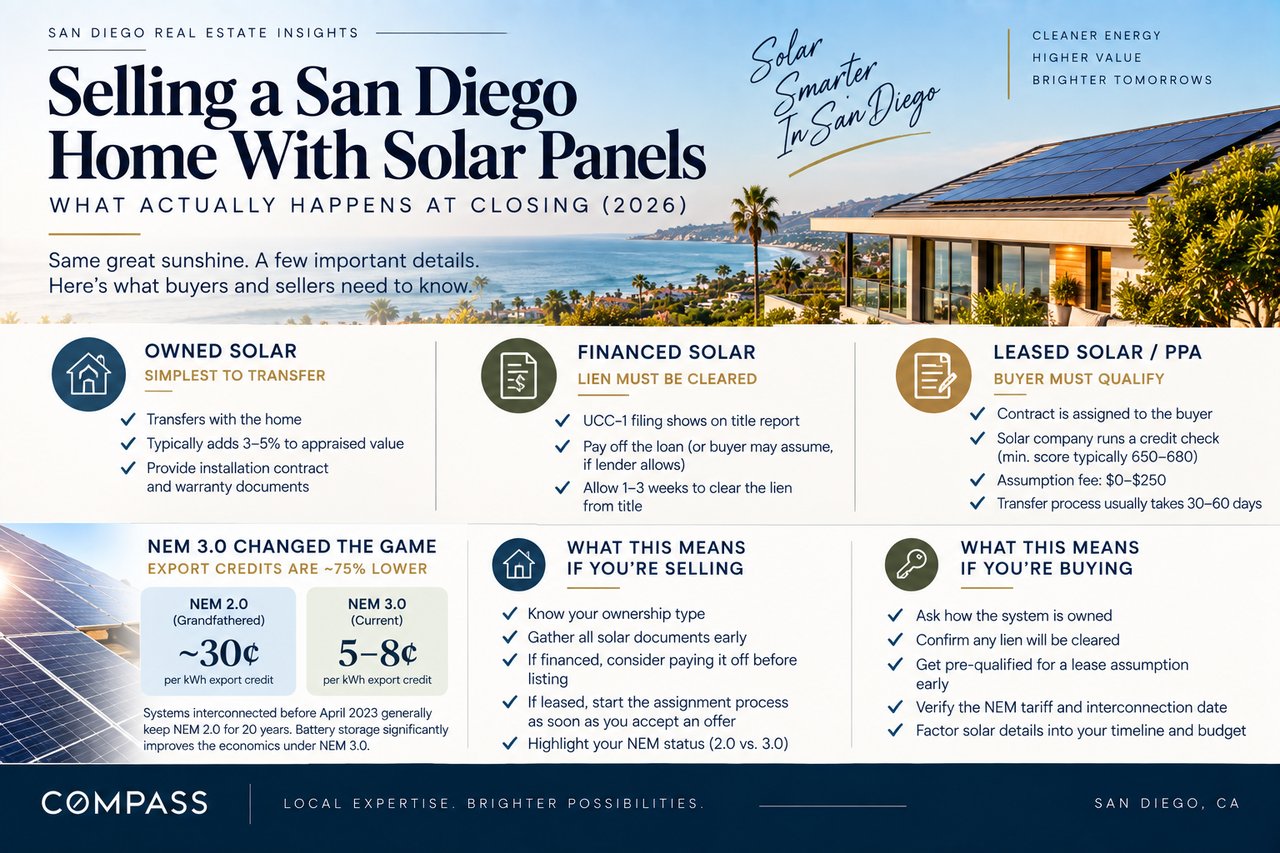
Selling a San Diego Home With Solar Panels: What Actually Happens at Closing (2026)
San Diego has one of the highest residential solar adoption rates in the country, which means a huge share of listings in this market come with a system already attached to the roof. What doesn't get explained nearly often enough is that "the house has solar" describes three genuinely different situations, owned outright, financed with a loan, or leased through a third party, and each one changes what happens at closing in a different way. Add in NEM 3.0's overhaul of how exported solar power gets credited, and a system that looked like a clear value-add two or three years ago can now be a more complicated selling point than either the buyer or seller expects.
The three ownership structures aren't interchangeable
The first question in any solar-equipped sale isn't how big the system is, it's how it's owned. A system purchased outright with cash is simply part of the home, no different from a new roof or a remodeled kitchen, and it transfers with the property the same way. A system purchased with a solar loan is a different animal: the lender typically files a UCC-1 fixture filing against the property at installation, which functions like a lien and shows up in the title report. A leased system, or one under a power purchase agreement where the homeowner pays for the electricity generated rather than owning the equipment, isn't part of the real property transaction at all, it's a service contract that has to be separately assigned to the buyer. Treating all three the same during a sale is exactly what causes deals to stall in escrow, since the actual steps required, and the actual value added, differ substantially between them.
Owned systems add real value, if you document it right
A solar system that's fully paid off and owned outright generally adds somewhere around 3 to 5 percent to a home's appraised value, depending on the system's size, age, and condition. Appraisers typically use an income approach to get there, calculating the present value of the energy savings the system is expected to generate going forward rather than simply adding back what the system originally cost. That means documentation matters as much as the hardware itself. California requires sellers to disclose solar system details as part of the standard Transfer Disclosure Statement, and for an owned system, including the original installation contract and any remaining manufacturer warranty in the disclosure package gives both the appraiser and the buyer's lender something concrete to work from rather than making them guess at the system's age and remaining useful life. A seller who can hand over clean paperwork on an owned system is protecting real appraised value that a messier file would leave on the table.
Financed systems carry a lien that has to be cleared before you close
If the panels were financed rather than paid for in cash, and there's still a balance owed, the solar lender's UCC-1 filing has to be resolved before a conventional loan can fund on the buyer's side. Fannie Mae and Freddie Mac both require that lien fully satisfied before closing, and even after the loan is paid off, getting the termination filing recorded and cleared from the title report typically takes one to three weeks, which needs to be built into your closing timeline rather than discovered midway through escrow. Sellers generally have two paths here: pay off the remaining loan balance at or before closing and get the UCC-1 termination filed, or have the buyer formally assume the loan if the solar lender allows it, which requires that lender's separate approval on top of everything else already happening in escrow. Paying it off ahead of time is almost always the cleaner path, since it removes an entire category of last-minute title complications that can delay or derail a closing date.
Leased systems and PPAs require the buyer to qualify, not just agree
This is the structure that trips up the most transactions, because a leased system or PPA isn't something a buyer simply inherits, it's a contract they have to be approved for. The solar company runs a credit check on the buyer, typically requiring a minimum score somewhere in the 650 to 680 range, and charges an assumption fee generally ranging from $0 to $250 to formally transfer the agreement. The transfer process itself usually takes 30 to 60 days and involves the solar company, the escrow officer, and sometimes a title company as well, running on a timeline that doesn't always match a standard 30-day close. It's also worth knowing that some mortgage lenders push back on financing a home with an active solar lease at all, treating the lease payment as a complicating factor in the buyer's overall debt profile, which can affect loan approval independent of the buyer's credit for the solar assumption itself. A seller with a leased system should start that assignment process the moment an offer is accepted, not after the buyer's loan is already moving through underwriting, since a 30 to 60 day parallel process left until late in escrow is a common reason solar-equipped closings get pushed back.
NEM 3.0 changed what a system is actually worth to a buyer
California's Net Billing Tariff, commonly called NEM 3.0, took effect in April 2023 and cut compensation for power exported back to the grid by roughly 75 percent, from crediting close to the retail rate, around 30 cents per kilowatt-hour under the old NEM 2.0 structure, down to an avoided-cost rate generally running 5 to 8 cents per kilowatt-hour today. That's a fundamental change in how much a solar-only system, without battery storage, actually saves a homeowner going forward, and it means a system's real value to a buyer now depends heavily on which tariff it's grandfathered under. Systems that were interconnected before the April 2023 cutoff generally keep their more favorable NEM 2.0 crediting for 20 years from the original interconnection date, which makes an older, grandfathered system genuinely more valuable to a buyer than an identical system installed today under NEM 3.0 rates. There's also a temporary bonus rate for early NEM 3.0 adopters, the ACC Plus adder, that steps down 20 percent each year through 2028, meaning even systems installed under the newer tariff are seeing their export compensation shrink further as that adder phases out. For a system without battery storage, payback periods have stretched out meaningfully under NEM 3.0, while systems paired with battery storage have held onto much stronger economics, since storing and using your own generation avoids the low export rate problem almost entirely. Buyers evaluating any solar-equipped listing should ask directly which tariff the system is grandfathered under and whether it includes storage, since those two facts affect the system's real value more than its age or panel count.
What this means if you're selling a home with solar
Know exactly which of the three ownership categories your system falls into before you list, and pull the paperwork, the original contract, warranty information, loan payoff details, or lease terms, well before you're in escrow rather than scrambling once a buyer asks. If your system is financed, get a payoff quote early and strongly consider clearing the UCC-1 before you're under contract, since that removes a real closing risk rather than leaving it for the buyer's lender to discover during underwriting. If it's leased, start the assignment and credit approval process the day you accept an offer, given the 30 to 60 day timeline involved. And know your system's NEM tariff and interconnection date, since a grandfathered NEM 2.0 system is a genuinely stronger selling point than a comparable NEM 3.0 system and it's worth highlighting explicitly rather than assuming buyers already understand the distinction.
What this means if you're buying a home with solar
Ask which ownership structure you're actually dealing with before you get attached to a listing, since an owned, financed, and leased system each require completely different steps and timelines to close. If there's a loan involved, confirm the UCC-1 has been or will be cleared before your own financing can fund. If it's leased, get pre-qualified for the assignment early in your own process, since your credit score for that assumption is separate from your mortgage approval and a low score on either side can hold up the deal. And ask directly about the system's NEM tariff and interconnection date, since a system still under NEM 2.0's more favorable crediting is worth meaningfully more to you going forward than one operating under current NEM 3.0 export rates, even if the two systems look identical on the roof.
The bottom line
A solar system can be a genuine value-add or a closing headache depending entirely on how it's owned and which net metering tariff it falls under, and treating every solar-equipped listing the same way is how deals end up delayed. Owned systems add real, appraisable value when the paperwork backs it up. Financed systems carry a lien that has to be resolved on a real timeline. Leased systems require the buyer to separately qualify through a process that runs alongside, not inside, your normal escrow timeline. If you're buying or selling a home with solar and want help sorting out exactly what you're dealing with, reach out and we'll go through the specifics together.