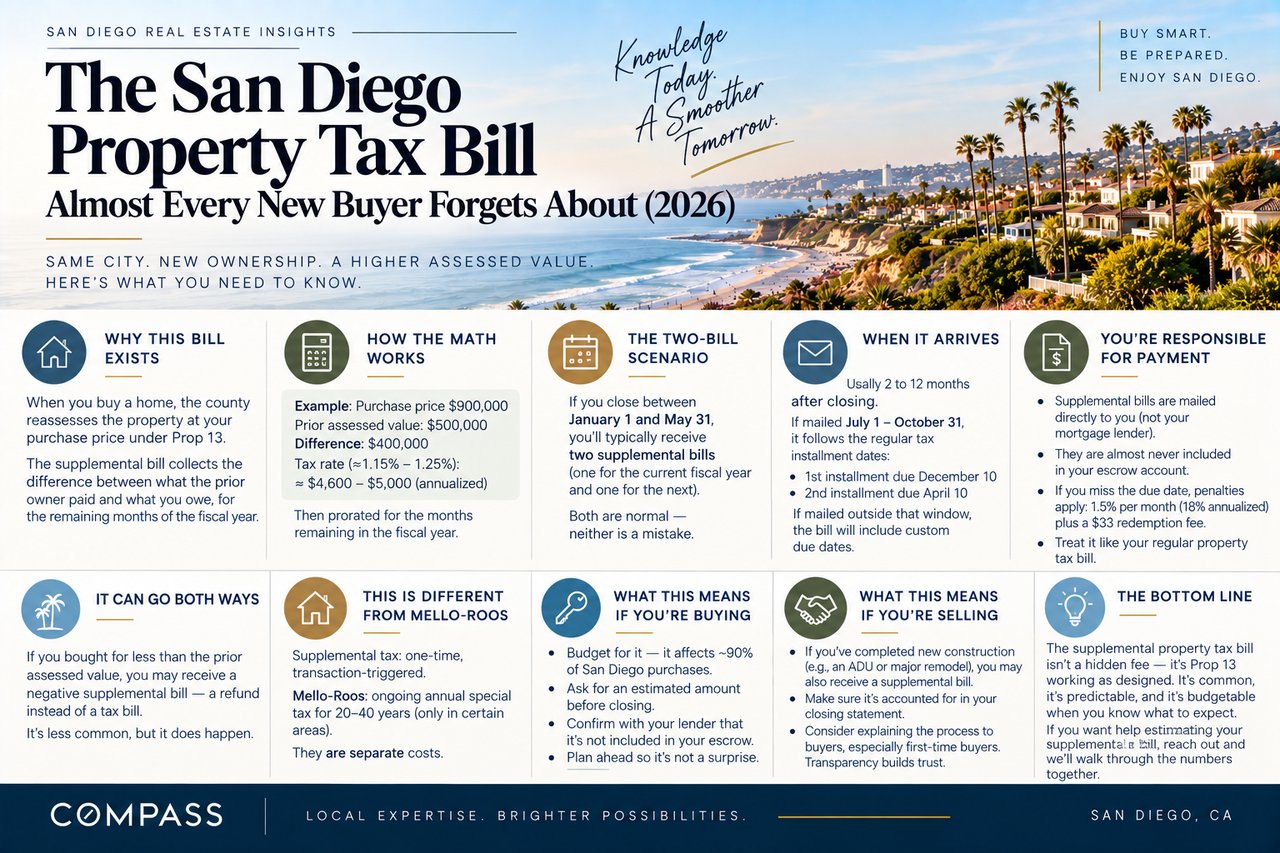
The San Diego Property Tax Bill Almost Every New Buyer Forgets About (2026)
Close on a home in San Diego and the property tax number you budgeted for is usually based on the old owner's assessed value, the one printed on the listing sheet or pulled from a quick county lookup. Months later, a separate bill shows up in the mail, addressed to you, for an amount nobody mentioned during escrow. This is the supplemental property tax bill, and according to county tax records it hits nearly 90 percent of San Diego home purchases. It isn't a scam, a mistake, or a hidden fee your agent should have caught, it's simply how California's reassessment system works, and it catches an enormous share of buyers off guard because almost nothing else about the closing process prepares you for a tax bill that arrives on its own timeline, addressed directly to you, and unconnected to your mortgage payment.
Why this bill exists at all
Under Prop 13, the rule covered in more detail elsewhere on this blog, a property's assessed value only changes in two situations: a change of ownership, or the completion of new construction. When you buy a home, the county assessor's office is required by state law to reassess it at your purchase price, replacing the prior owner's Prop 13 basis with a new one that reflects what you actually paid. The problem is timing. The regular property tax bill for a given fiscal year, which runs July 1 through June 30, is generated off whatever assessed value was on file at the start of that cycle, which is almost always the prior owner's lower number if you bought partway through the year. The supplemental bill exists specifically to close that gap, capturing the difference between what the old owner was taxed on and what you should have been taxed on, for the remaining months of that fiscal year. The exact same mechanism applies if you complete new construction on a property you already own, an ADU addition being the most common example, which means the reassessment logic covered in the ADU cost breakdown elsewhere on this blog and this supplemental bill are two sides of the same underlying rule.
How the math actually works
The calculation is more mechanical than it sounds once you see it worked through. Say you buy a home for $900,000, and the prior owner's assessed value was $500,000. The difference, $400,000, is your supplemental assessment value. Multiply that by your property's combined local tax rate, typically somewhere around 1.15 to 1.25 percent in most of San Diego County once base rate and any voter-approved bonds are included, and you get the annualized supplemental amount, roughly $4,600 to $5,000 a year in this example. That figure then gets prorated for however many months remain in the fiscal year from your close of escrow through June 30. Close on January 1 and you're only responsible for the prorated half of that annual figure, close in July and you're closer to owing the full amount, since nearly the entire fiscal year remains ahead of you.
The two-bill trap for anyone closing between January and May
One timing detail surprises even buyers who've done their homework. If you close escrow between January 1 and May 31, the county has to true up two overlapping fiscal years at once, since your reassessment affects both the tax roll that's already in progress and the one about to begin July 1. That means buyers in this window typically receive two separate supplemental bills rather than one, arriving close together but calculated against two different periods. Neither bill is a mistake or a duplicate charge, but seeing two unfamiliar tax bills land around the same time is exactly the kind of thing that makes a first-time buyer assume something went wrong when nothing has.
When it actually arrives, and why the timeline feels so long
Supplemental bills don't arrive quickly. Depending on how backed up the assessor's office is at any given time, they're generally mailed out somewhere between a few months and up to roughly a year after your close of escrow or the completion of new construction. That gap is long enough that plenty of buyers have genuinely forgotten the bill is coming by the time it shows up, which is part of why it feels like a surprise rather than an anticipated cost. If the county mails your bill between July 1 and October 31, the payment installments generally align with the regular property tax calendar, first installment due December 10, second due April 10. If it's mailed outside that window, the county sets different due dates specific to that bill, and those dates are printed directly on the notice rather than following the standard calendar, so the actual bill in hand, not a general rule of thumb, is what determines your deadline.
Nobody else is going to pay this for you
This is the detail that trips up the most new owners: unlike your regular annual property tax bill, which your mortgage lender often collects through an impound or escrow account and pays on your behalf, supplemental tax bills are mailed directly to the property owner and are almost never included in that escrow arrangement. Your lender isn't tracking it, isn't budgeting for it in your monthly payment, and in most cases doesn't even see it. If you miss a due date, the consequences are real. Once a supplemental installment goes unpaid past the deadline, the account moves toward default, and unpaid supplemental taxes accrue a penalty of 1.5 percent per month, 18 percent annualized, plus a flat redemption fee of $33 once the account is in default. Treat this bill with the same seriousness as your regular tax installments, because the county does.
Not every supplemental bill increases what you owe
If you bought your home for less than its prior assessed value, which can happen in a softening market or with a distressed sale, the reassessment works in your favor and produces what's called a negative supplemental bill. Rather than owing additional tax, you receive a refund check for the difference, which can be applied against any other open balance on the parcel or issued directly to you. It's a smaller share of transactions than the standard positive supplemental bill, but it's worth knowing the mechanism runs in both directions rather than assuming every reassessment automatically means a bigger check written to the county.
How this differs from Mello-Roos
It's easy to lump every unfamiliar line item on a San Diego tax bill into one category, but the supplemental bill and a Mello-Roos assessment, covered in more detail elsewhere on this blog, are entirely different mechanisms. Mello-Roos is an ongoing annual special tax tied to a Community Facilities District bond, showing up on your regular tax bill every year for the life of the bond, often 20 to 40 years, regardless of who owns the property. The supplemental bill is a one-time, transaction-triggered charge tied specifically to your purchase or your new construction, and once it's paid, it doesn't recur unless you sell again or build something new. A buyer comparing two similarly priced homes, one in a Mello-Roos district and one without, needs to think about both costs separately: the supplemental bill is a near-term, one-time expense every buyer in the county should expect, while Mello-Roos is a much longer-term, property-specific carrying cost that only applies to certain communities.
What this means if you're buying in San Diego right now
Budget for this bill the same way you'd budget for a security deposit or moving costs, as a real, near-certain cost rather than a hypothetical one, since it affects close to 9 out of 10 purchases countywide. Ask your agent or title company for an estimated supplemental amount before you close, using the gap between the seller's current assessed value and your purchase price, so the eventual bill isn't a complete surprise even if the exact figure and timing aren't final until the county mails it. And don't assume your mortgage servicer has this covered simply because your regular property taxes are impounded, confirm directly with your lender whether supplemental bills fall outside that arrangement, because for the overwhelming majority of San Diego buyers, they do.
What this means if you're selling in San Diego right now
If you've completed a significant addition, an ADU, a major remodel that triggered new construction reassessment, expect your own supplemental bill to show up on your account before or even after your sale closes, and make sure it's accounted for in your closing statement rather than left as a loose end. It's also worth proactively explaining the supplemental tax mechanism to buyers during your transaction, particularly first-time buyers, since a seller who volunteers this information looks far more credible than one who lets a buyer discover it on their own months after closing and wonder whether something was hidden from them.
The bottom line
The supplemental property tax bill isn't a fee anyone invented to catch buyers off guard, it's simply Prop 13's reassessment rule working exactly as designed, closing the gap between what the prior owner was taxed on and what you actually paid. It hits nearly every San Diego purchase, it arrives on its own schedule months after closing, it's never automatically covered by your mortgage escrow, and missing the due date carries real penalties. Knowing the mechanics, the rough math, the two-bill scenario for early-year closings, and who's actually responsible for paying it turns a confusing surprise into a predictable, budgetable cost. If you want help estimating what your own supplemental bill is likely to look like before or after a purchase, reach out and we'll walk through the numbers together.