Can You Lower Your San Diego Property Taxes? The Prop 8 Appeal Explained (2026)
If you bought a condo near the top of the market in 2021 or 2022, there's a real chance you're paying property tax on a value your home hasn't been worth in years. San Diego's attached housing market has softened noticeably since then, with the countywide median for condos and townhomes down to $675,000 as of May 2026, and older units in HOA communities off 10 to 15 percent or more from their 2022 highs. Meanwhile, your Prop 13 assessed value is still locked to whatever you paid at the peak. California has a mechanism built specifically for this gap, commonly called a Prop 8 appeal, and the filing window for this tax year closes November 30, 2026.
What Prop 8 actually does, and who it's for
Proposition 8, passed in 1978 as a companion to Prop 13, requires the county to temporarily lower a property's assessed value whenever current market value falls below the factored Prop 13 base year value, meaning what you originally paid plus up to 2 percent annual growth since then. The assessor measures this every year as of the January 1 lien date, so a Prop 8 adjustment for the 2026-27 tax year is based on where your home's value stood on January 1, 2026, not where it stands today.
This only helps a specific slice of owners, and it's worth being honest about who that is. If you bought decades ago, your assessed value is almost certainly still far below current market value even after a 10 or 15 percent condo correction, since Prop 13's 2 percent cap has kept your taxable value from ever catching up to the market in the first place. Prop 8 relief is really aimed at people who bought closer to a market peak, where the gap between purchase price and today's value has genuinely gone negative. Given the timing of San Diego's condo softening relative to the 2021-2022 peak, that describes a meaningful number of recent condo and townhome buyers right now, more than it describes detached home buyers, since single family inventory has stayed tight and prices there have mostly held.
Two ways to file, and both are free
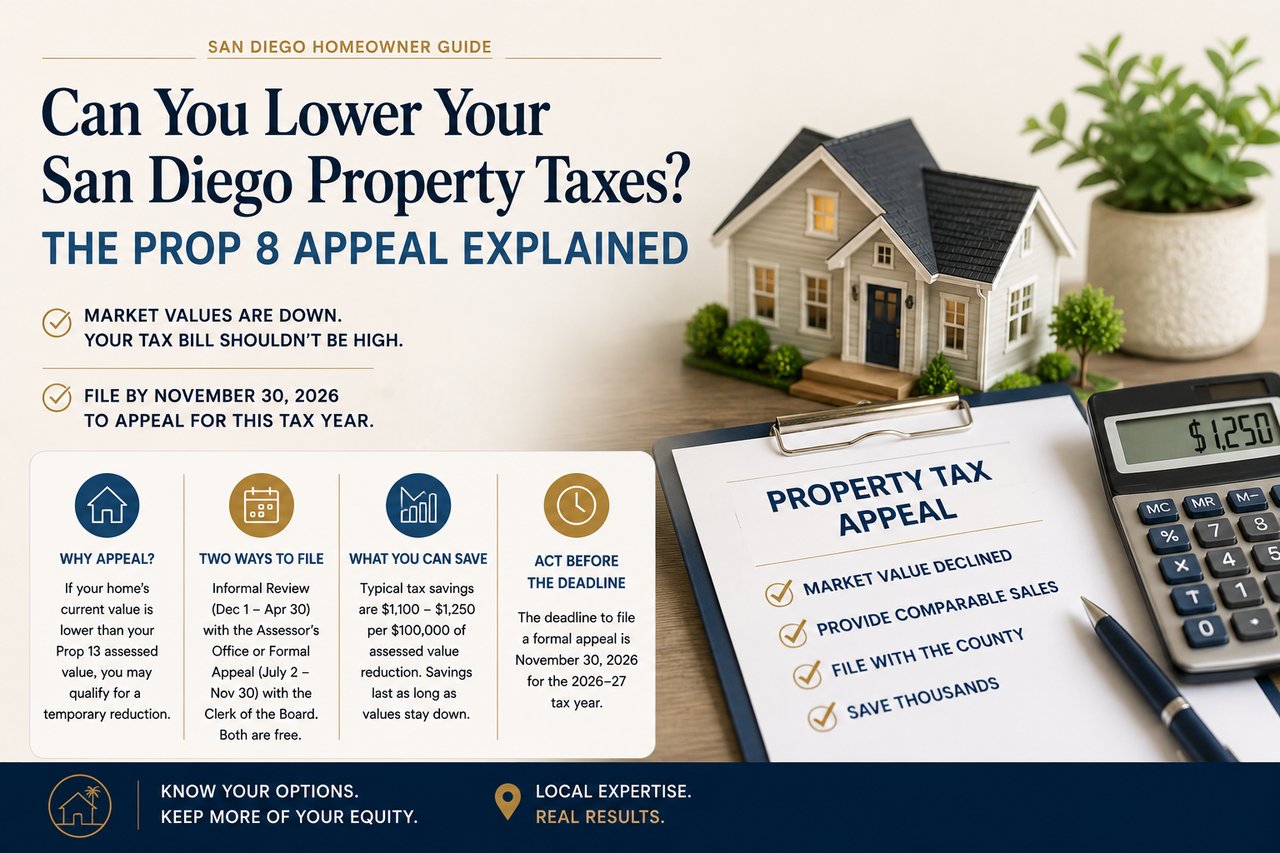
San Diego County offers two separate paths, and they run on different calendars. The informal Decline-in-Value Review goes directly through the Assessor's Office, runs from December 1 through April 30, requires no formal application or fee, and simply asks you to submit your case along with comparable sales supporting a lower value. The Assessor reviews it and adjusts the roll if the evidence supports it, without ever going to a hearing.
The formal path is the Assessment Appeal Application, form BOE-305-AH, filed with the Clerk of the Board rather than the Assessor directly. That window runs July 2 through November 30 each year, also with no filing fee, but it requires an original signature and has to be filed by mail or in person at the Clerk of the Board's office on Pacific Highway. If the Assessor's Office doesn't agree to adjust your value informally, or you'd rather go straight to a binding appeal, this is the route, and it comes with one hard requirement: you or an authorized agent has to actually show up at the hearing, or the case gets denied by default. A number of paid tax-appeal firms advertise this service, but nothing about the process requires hiring one. Both paths are designed to be filed directly by the property owner.
The evidence that actually moves the needle
What convinces an assessor or an appeals board is comparable sales, ideally close to the January 1 lien date the assessment is actually based on, not whatever the market is doing the week you file. For a condo or townhome, that means pulling closed sales in your building or in genuinely comparable buildings nearby from late 2025 into early 2026, not September 2026 listings. This is also where the specific cost pressures driving condo softening matter. If your building has HOA dues that have climbed sharply, a pending SB 326 balcony inspection report flagging expensive repairs, or an insurance renewal that spiked, those factors are exactly what's been pushing comparable sale prices down, and documenting them alongside your comps strengthens the case that your unit's value has genuinely declined rather than just having a few weak comps.
The Assessor already does some of this automatically, but don't count on it
California law actually requires assessors to enroll the lower of the factored Prop 13 value or current market value every year, without waiting for an application. In theory, some Prop 8 reductions happen automatically. In practice, the Assessor's Office is working with a countywide roll covering hundreds of thousands of parcels, and it can't individually re-appraise every condo in every HOA community each year. Broad neighborhood-level declines tend to get caught more reliably than building-specific issues like a large pending special assessment or a building-specific insurance problem, which is exactly the kind of detail an owner is in a much better position to document than a countywide mass appraisal process is likely to catch. Filing your own review or appeal is what puts your specific numbers, and your building's specific problems, directly in front of someone who will actually look at them.
What happens after you win: it's temporary, and it can bounce back fast
A Prop 8 reduction isn't a permanent rewrite of your tax basis, it's a temporary adjustment that gets reevaluated every January 1 alongside everyone else's. If the market recovers, your assessed value can be raised back up, and here's the detail that surprises people: once you're under a Prop 8 reduction, the normal 2 percent annual growth cap doesn't apply on the way back up. The assessor can restore your value by more than 2 percent in a single year, as fast as the market actually recovers, until it catches back up to what your original Prop 13 factored base would have grown to if the reduction had never happened. Once it catches up, you're back under the normal 2 percent cap going forward. It's a real benefit while your value is genuinely depressed, but it's not a strategy for locking in a lower tax bill long term the way the original purchase-price basis works.
Is it actually worth the effort
Run the math before you file. San Diego's effective property tax rate, once local bonds and assessments are included, typically lands somewhere between 1.1 and 1.25 percent of assessed value. If your condo's current value has genuinely fallen $100,000 below your Prop 13 assessed value, that's roughly $1,100 to $1,250 a year in tax savings, recurring for as long as the reduction lasts. The informal review costs nothing but the time to pull comps and submit a request, which makes it worth doing anytime the gap looks real. The formal appeal is also free, but requires more paperwork and a hearing appearance, so it's worth reserving for cases where the informal review didn't resolve things or the deadline for that year's informal window has already passed.
What this means if you bought a condo near the 2021-2022 peak
Pull your closing statement to confirm your actual purchase price and current assessed value, then compare it against recent closed sales in your building or a genuinely comparable one nearby. If your unit's current value looks meaningfully below your assessed value, especially once you account for rising HOA dues, a pending SB 326 inspection finding, or a recent insurance jump in your building, you're a strong candidate for at least the informal Decline-in-Value Review this coming December through April. If you'd rather not wait for that window, or you want the binding weight of a formal appeal, the November 30, 2026 deadline for this tax year is coming up, and filing costs nothing but the paperwork and a hearing date.
What this means if you've owned for a decade or more
Prop 8 is unlikely to apply to you, since your Prop 13 basis has almost certainly stayed well below current market value even through a real correction. Where this still matters for long-time owners is indirectly: if you're watching the condo market soften and wondering whether it affects your own tax bill, it generally doesn't, because the gap between your low assessed value and even a reduced market value is still likely to favor the assessed value staying put. The exception is if you've made major improvements recently, since new construction gets its own separate assessment that isn't protected by your original low basis.
Getting your specific numbers right
Whether a Prop 8 appeal makes sense comes down to your specific purchase price, your building's current comps, and how much your HOA's costs have moved since you bought. If you want help pulling comparable sales near the January 1 lien date, sizing up whether the gap between your assessed value and current market value is worth pursuing, or walking through the informal review versus formal appeal decision, reach out and we'll go through the numbers together before the window closes.