How Prop 13 Actually Sets Your San Diego Property Tax Bill in 2026
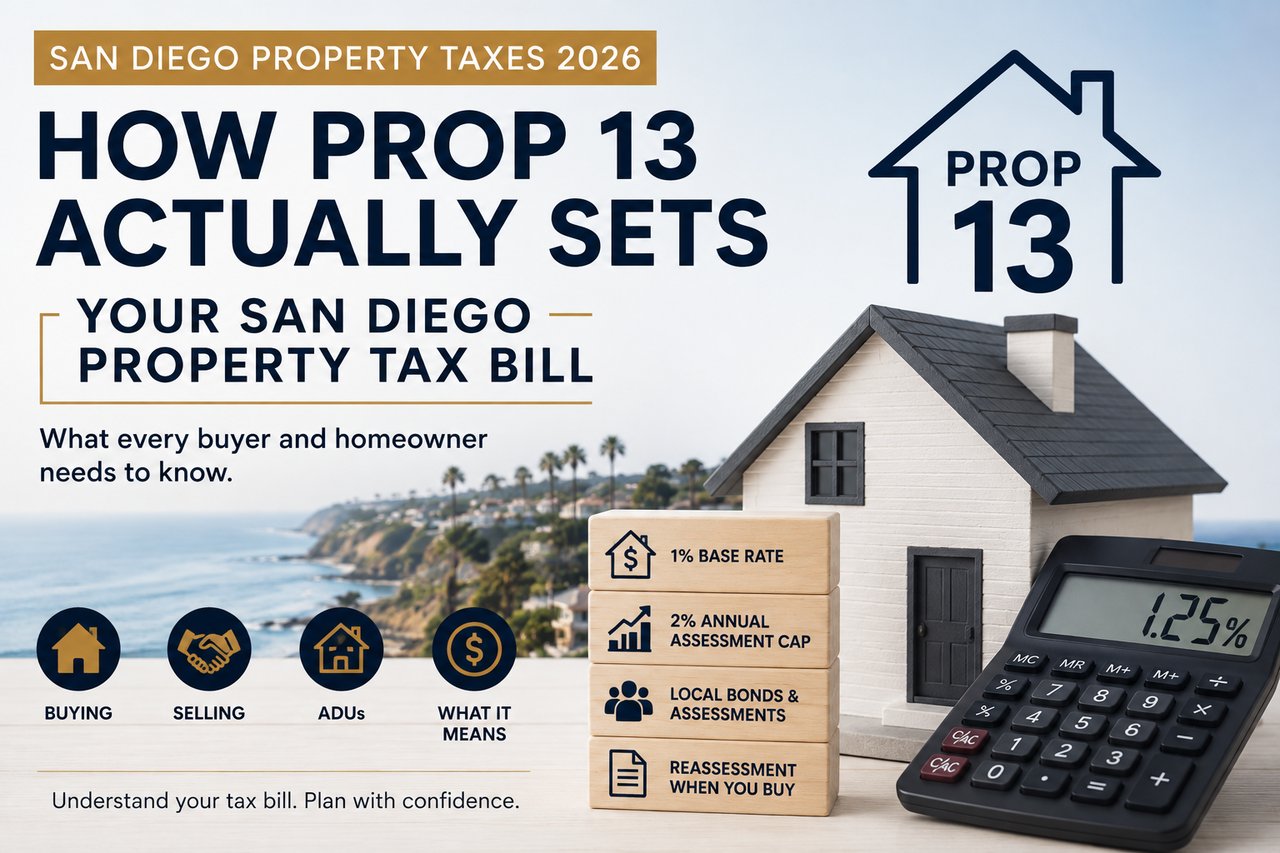
Most San Diego buyers know property tax is "around 1 percent," and then their first bill doesn't match that number and they're not sure why. The short answer: Prop 13 sets the 1 percent base rate and caps how fast your assessed value can grow, but it doesn't cap the voter-approved bonds and local assessments layered on top, and it doesn't protect you from a full reassessment the moment you buy. Here's how the pieces actually fit together.
The 1 percent base rate
California's Proposition 13, passed in 1978, is still the foundation of every property tax bill in the state. It does two things. First, it caps the general property tax rate at 1 percent of a property's assessed value. Second, it limits how much that assessed value can increase each year, generally no more than 2 percent, regardless of how much the home's actual market value rises. That second part is the more consequential one over time. A home bought in 2010 for $400,000 might have an assessed value today that's still well under its current market price, because the 2 percent annual cap has kept the taxable value from tracking the market. That's also why two nearly identical homes on the same block can carry very different tax bills depending on when each one last changed hands.
Why your actual bill is higher than 1 percent
The 1 percent base is only the starting point, not the final number. On top of it, voter-approved general obligation bonds for schools and infrastructure, along with local assessments, get added in. For most San Diego homeowners, that pushes the effective rate to somewhere between 1.1 and 1.25 percent of assessed value once everything is included. In newer communities with Mello-Roos special tax districts, the effective rate can run past 1.3 percent, sometimes well past it. Because school district and assessment district boundaries don't follow city limits, the exact rate varies by zip code and occasionally by neighborhood within the same city, which is why pulling the actual parcel tax history matters more than assuming a countywide average applies to a specific address. San Diego County's total assessed value reached $845 billion in 2026, and that steady growth is exactly why understanding what sits on top of the base 1 percent matters, since local bonds and assessments are what make up the difference between the advertised rate and the real one.
Reassessment: what actually resets your tax basis
Prop 13's 2 percent annual cap only applies as long as ownership doesn't change. The moment a property sells, the county reassesses it at the new purchase price, wiping out whatever benefit the previous owner had built up from years of capped growth. This is the single most important thing for buyers to understand about their first year of ownership: your tax bill isn't based on what the seller was paying, it's based on what you paid.
That reassessment triggers a supplemental property tax bill, separate from the regular annual bill, that most buyers don't budget for. The county takes the new purchase price, subtracts the seller's prior assessed value, multiplies that difference by the local rate of roughly 1.1 to 1.25 percent, and prorates the result based on how many months are left in the tax year from the closing date. In a market like San Diego, where plenty of sellers have owned for a decade or more, that gap between old and new assessed value can be substantial, and the supplemental bill often arrives three to six months after closing, well after a new owner has settled into a monthly budget built around the regular tax bill alone. Setting aside funds for this in advance, especially on a home that hasn't changed hands recently, avoids an unpleasant surprise.
What building an ADU does to your assessment
Adding an accessory dwelling unit doesn't touch the Prop 13 basis on the rest of your property. The county reassesses only the value of the new construction itself, leaving your original assessed value on the existing home untouched. As a rough guide, a $200,000 ADU addition typically adds somewhere in the range of $2,000 to $2,500 a year to the property tax bill, which is generally modest relative to the rental income or added living space most ADUs are built to provide. This partial reassessment rule is a direct result of how Prop 13 defines what counts as a change in ownership versus new construction, and it's worth knowing before you assume an ADU will trigger a full reassessment of the whole property. It won't.
What this means if you're buying
Don't anchor your tax estimate to what the current owner is paying. Ask your agent or the county assessor for the actual effective rate on the specific parcel, factor in a supplemental bill that will likely arrive a few months after closing, and remember that your first full year of ownership is the one where the reassessment gap is largest. If a home has been owned by the same family for twenty or thirty years, expect the supplemental bill to be meaningfully larger than it would be on a home that last sold five years ago.
What this means if you're selling
Buyers increasingly understand that your low, long-held assessed value doesn't transfer with the house, so pricing based on your own tax bill as a selling point rarely lands the way sellers hope. What does help is being upfront about the actual effective rate for the property, including any bonds or assessments specific to the neighborhood, so buyers can budget accurately rather than discovering the real number after they're in escrow.
Getting your specific number right
The 1 percent headline rate is a starting point, not the number that will show up on your bill. Between local bonds, assessment districts, the reassessment that happens at sale, and how ADUs get valued, the real math is specific to each parcel. If you want help pulling the actual effective rate and reassessment history on a property you're considering, reach out and we'll go through it together before you're under contract.