How to Sell an Inherited House in San Diego (2026): Probate, Taxes, and What Actually Slows These Deals Down
Selling a home you inherited is nothing like selling a home you bought yourself, and the gap catches most people off guard. You're often dealing with a house that's been owned by the same family for decades, a probate court that may or may not need to sign off before you can list it, two completely separate tax systems that don't talk to each other, and sometimes siblings who don't agree on what to do next. San Diego has an unusually large share of these situations right now, because so many long-time owners bought decades ago and their homes have appreciated well past what anyone expected. Here's what the process actually looks like in 2026, and where it tends to get stuck.
Do you even have to go through probate first
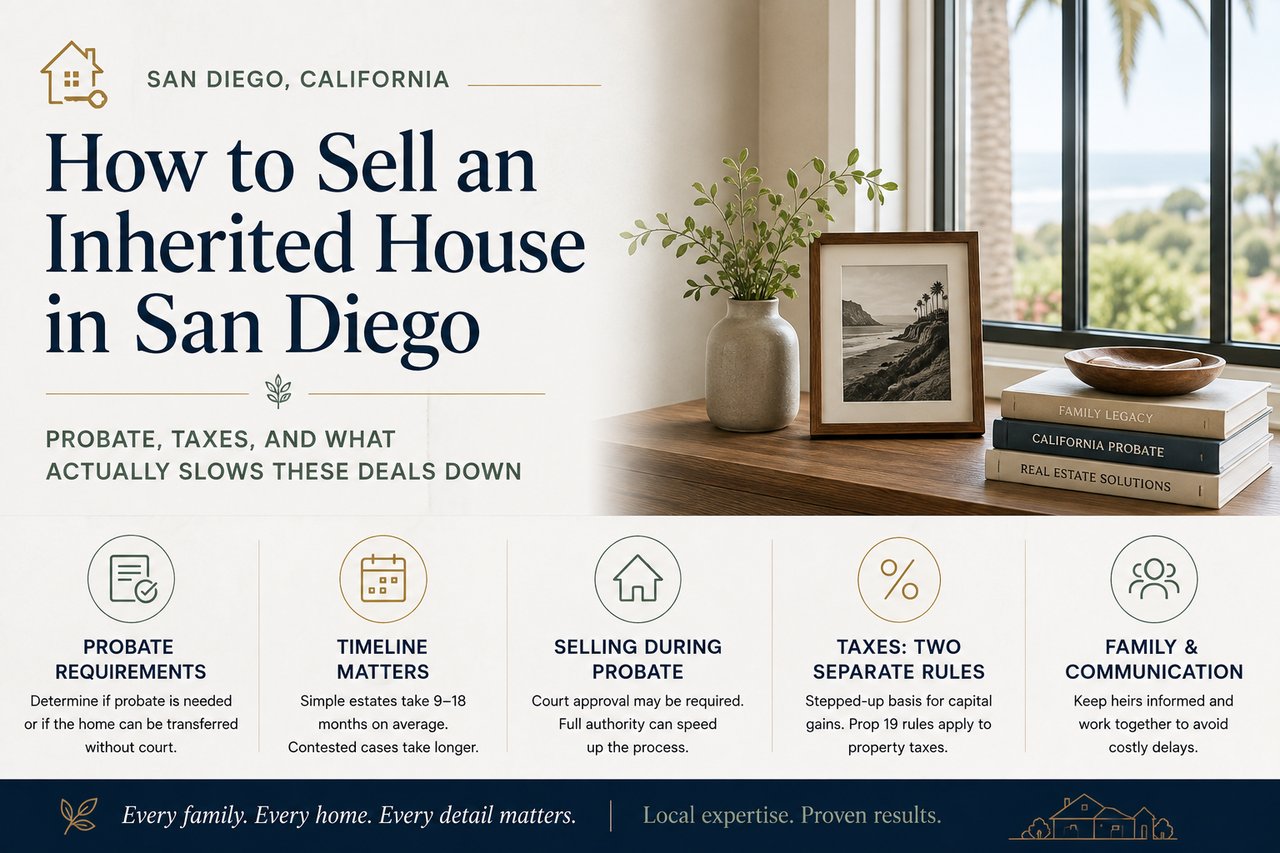
The first question isn't how to sell the house, it's whether you're legally able to sell it yet. If the home was held in a revocable living trust, the trustee can typically sell it directly without court involvement at all, which is the cleanest path and one more reason trusts have become the default estate planning tool for anyone who owns real property in California. If there's no trust, the answer depends on the value of the estate and how title was held.
California created a genuinely useful shortcut in recent years for a decedent's primary residence specifically. Under a Petition to Determine Succession to Real Property, heirs can transfer a primary residence worth up to $750,000 without opening a full probate case, using a simplified court petition instead. That threshold sounds generous until you remember what San Diego homes actually cost. A starter home in parts of the county still slides under that number, but anything in Carmel Valley, Del Mar, or most of the coast is going to blow past it, which means full probate is often unavoidable here even when it wouldn't be in a cheaper part of the state.
For estates without real property, or with only modest personal property, there's a separate small estate affidavit process. For deaths between April 1, 2025 and March 31, 2026, that threshold sits at $208,850, rising to $239,700 for deaths on or after April 1, 2026. But that figure covers personal property, not real estate. Real property gets its own, much smaller carve-out: an Affidavit Re Real Property of Small Value, available only when the real property interest is worth less than roughly $69,625, and even then you have to wait six months from the date of death before filing it. In practice, almost no San Diego home qualifies for this option, so if there's no trust and the home is worth anything close to current market value, plan on full probate.
If full probate is required, here's the timeline you're working with
This is the part that surprises people the most. San Diego runs one of the busiest probate calendars in the state, with over 2,300 estate and trust filings in the most recent fiscal year alone, and that volume shows up directly in how long cases take. Simple, uncontested estates typically run 9 to 12 months from filing to close. Average estates run 12 to 18 months. Anything contested, whether over the will, the executor, or how assets get divided among heirs, can stretch past two years.
Some of this delay is baked into the process and can't be rushed. California law requires a mandatory four-month window after the personal representative is appointed for creditors to file claims against the estate, and that clock doesn't start until appointment happens, which itself typically takes six to eight weeks to reach a first hearing on a crowded San Diego calendar. None of this means the house can't be listed and sold during probate, it usually can be, but it does mean the sale is happening inside a legal process with its own pace, not on the seller's preferred timeline.
Selling during probate: what the process actually looks like
How much court oversight your sale needs comes down to one specific detail: whether the executor or administrator was granted full or limited authority under the Independent Administration of Estates Act, generally referred to as IAEA. With limited authority, every sale of real property needs court confirmation, which in California probate can mean an unusual final step called overbidding, where the court hearing to confirm the sale is opened up to other buyers who can outbid the accepted offer by a statutory minimum, sometimes turning what felt like a done deal into a live auction in a courtroom.
With full IAEA authority, which is what most experienced probate attorneys request from the start, the process moves considerably faster. The personal representative can negotiate and accept an offer without a court hearing at all. Instead, a Notice of Proposed Action goes out to all heirs disclosing the price and terms, and if no heir objects within 15 days, the sale proceeds without ever going in front of a judge. This is the single biggest lever for speeding up a probate sale, and it's worth confirming with the estate's attorney early which type of authority the personal representative actually has, since it changes the entire timeline for getting an accepted offer to the closing table.
The tax side: two systems that don't talk to each other
Inherited property sits at the intersection of two completely separate tax questions, and mixing them up leads to bad assumptions on both sides. On the capital gains side, an inherited home gets a stepped-up cost basis equal to its fair market value on the date of death, under federal rule IRC 1014. That step-up wipes out essentially all the appreciation that built up while the original owner held the property, so if you sell relatively soon after inheriting, you'll typically owe little to no capital gains tax even if the home was purchased decades ago for a fraction of today's price. Getting a professional appraisal or documented valuation as close to the date of death as possible is the single most useful thing you can do here, since that number becomes your basis and directly determines your eventual tax bill.
Property tax runs on an entirely different set of rules under Prop 19, and it doesn't care about your capital gains basis at all. If you move into the inherited home as your primary residence within one year and file for the homeowners' exemption, you can retain a version of the parent's original tax basis, but only up to a cap that currently sits at $1,044,586 above the original assessed value for transfers occurring through February 2027. If you don't move in within that year, or the home's appreciation exceeds the cap, the county reassesses the property to full current market value, which on a long-held San Diego home can mean a dramatic jump in the annual tax bill almost overnight. These two systems produce genuinely different answers, and it's worth treating them as two separate homework assignments rather than assuming a good outcome on one tells you anything about the other.
Reverse mortgages: the wrinkle most heirs don't see coming
A meaningful share of older San Diego homeowners carry a reverse mortgage, and if the home you inherited has one, it changes your timeline whether you're ready or not. A federally insured HECM reverse mortgage becomes due and payable when the last borrower passes away, and the lender is required to notify heirs of that fact. From there, heirs generally have a narrow window, often 30 days initially, though extensions are commonly available in increments that can stretch to six months or slightly beyond, to either pay off the loan, refinance it, or sell the home and use the proceeds to satisfy the debt. Because these loans are non-recourse, if the home is worth less than the outstanding balance, heirs can typically satisfy the debt by selling for at least 95 percent of the current appraised value rather than owing the difference out of pocket. If you're dealing with an inherited home and aren't sure whether it carries a reverse mortgage, that's one of the first things to confirm, since it can compress your selling timeline well below what probate alone would otherwise allow.
When multiple heirs don't agree
Inherited homes frequently pass to two or more siblings jointly, and disagreement about what to do next is one of the most common things that stalls these sales. Broadly, there are three paths. One heir can buy out the others' shares, usually based on a professional appraisal and often requiring that heir to refinance or take out a new loan to raise the cash. All heirs can agree to sell and split the proceeds according to their ownership percentage, which is by far the most common outcome, particularly when no single heir wants to live in the home or can afford to maintain it alone. Or, when heirs genuinely can't reach agreement, any co-owner can file a partition action asking the court to force a sale and divide the proceeds. Partition actions work, but they're slower and more expensive than a cooperative sale, often adding months and legal fees that come directly out of everyone's share. Getting ahead of this conversation early, ideally before the home is even ready to list, tends to save both time and money compared to letting disagreement surface mid-transaction.
Getting the house ready to sell
Inherited homes are often owned for twenty, thirty, or more years by the time they change hands, which usually means some combination of deferred maintenance, dated finishes, and a full house of belongings that needs to be cleared before it can be shown. Heirs generally face a real choice here: invest time and money into repairs and staging to sell at full retail value, or sell as-is to a cash buyer for a faster, lower-friction transaction at a discount to market value. Neither option is automatically right. A home in a strong San Diego neighborhood with straightforward cosmetic issues often nets meaningfully more after a modest repair investment, while a home with significant deferred maintenance, or heirs who live out of the area and can't manage a renovation, may come out ahead selling as-is once the time value and hassle of a longer process gets factored in. Either way, clearing the estate's contents, confirming there are no outstanding liens or judgments against the property, and lining up the standard California disclosure package early keeps the sale from stalling once an offer comes in.
What this means if you're managing an inherited home right now
Start by figuring out which category you're in: trust property that can move without probate, an estate that might qualify for the simplified primary residence petition under the $750,000 threshold, or a full probate case that's going to run on its own timeline. Get a professional date-of-death valuation before anything else, since it protects your capital gains position no matter which path the property takes. Check the Prop 19 one-year move-in deadline immediately if staying in the home is even a possibility, since that clock doesn't wait for probate to finish. And if there's a reverse mortgage or more than one heir involved, have those conversations early rather than letting them surface for the first time once an offer is already on the table.
Figuring out what your specific situation looks like
Every inherited home carries its own combination of probate status, tax basis, and family dynamics, and the right sequence of steps depends on getting those specifics right from the start. If you're navigating an inherited San Diego property and want help thinking through the probate timeline, the tax numbers, or how to prepare the home for sale, reach out and we'll walk through what makes sense for your situation.