Prop 19 in San Diego: How to Transfer Your Tax Basis, and What Changed for Inherited Homes (2026)
Prop 19 works two very different ways depending on which side of a transaction you're on, and both sides matter for San Diego homeowners right now. If you're 55 or older, severely disabled, or a wildfire or disaster victim, Prop 19 lets you carry your old, low property tax basis to a new home anywhere in California, up to three times. If you're inheriting a home from a parent, Prop 19 also made that transfer significantly less generous than it used to be. Here's how each side actually works in 2026.
Taking your tax basis with you when you downsize
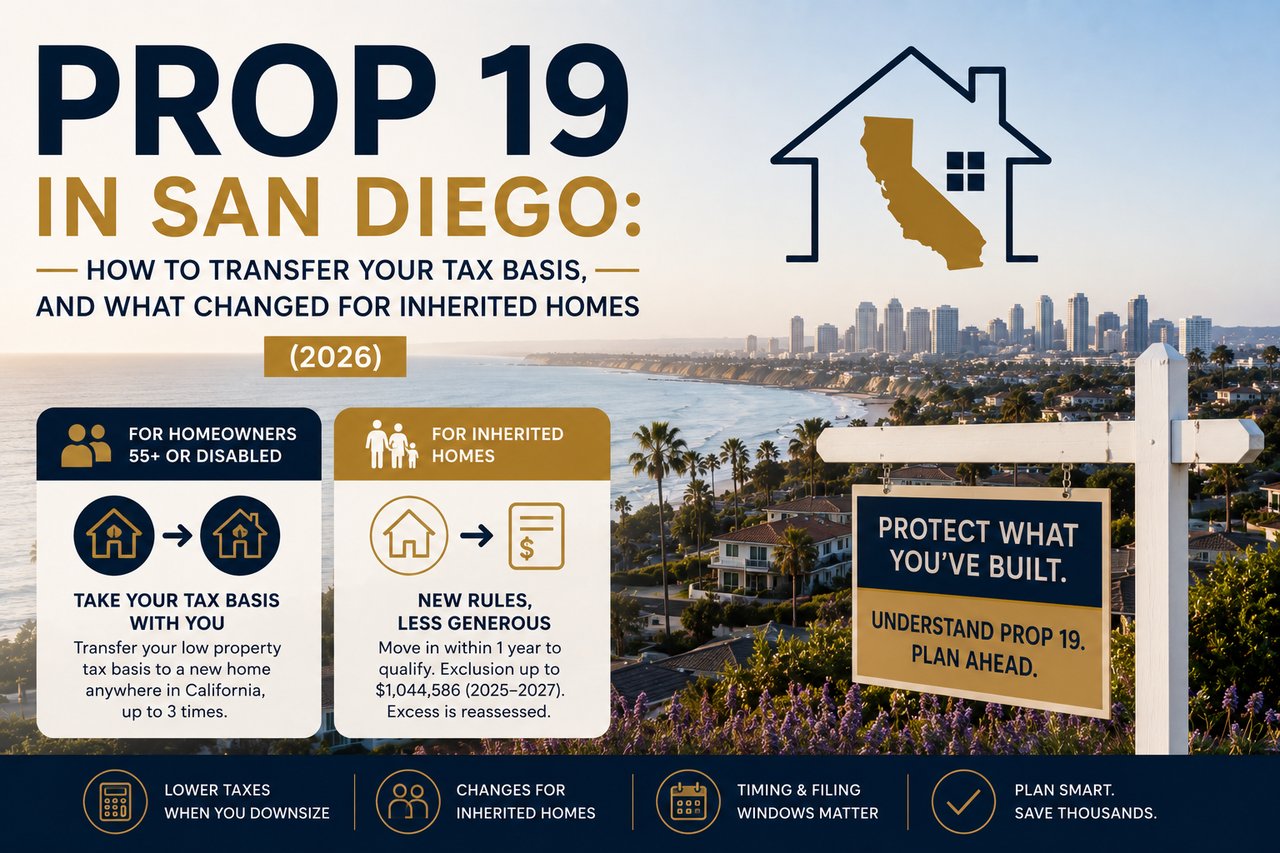
Effective since February 2021, Prop 19 allows homeowners who are 55 or older, severely disabled, or victims of a wildfire or other governor-declared disaster to transfer the assessed value, meaning the Prop 13 tax basis, of their current primary residence to a replacement primary residence anywhere in California. This can be done up to three times for age or disability, with no limit on the number of transfers for disaster victims.
This matters enormously for anyone who has owned a San Diego home for twenty or thirty years. Without Prop 19, selling that home and buying a smaller one would trigger a full reassessment at current market value, potentially tripling or quadrupling the annual tax bill even on a less expensive replacement property. With Prop 19, the old assessed value moves with you. If the replacement home costs more than the one you sold, the difference in price gets added to the transferred base, so the benefit scales down as the price gap widens, but it doesn't disappear entirely just because the new home costs more.
There's a filing window that matters here. Claims generally need to be filed within a few years of purchasing the replacement home to lock in the transferred basis retroactively to the purchase date, and both the original and replacement properties need to meet specific occupancy and timing requirements, including that the original home must have been your principal residence and must be sold as part of the process. Anyone planning a move like this should loop in a tax professional or the county assessor's office early, well before listing the original home, rather than trying to sort out the paperwork after the fact.
What changed for inherited homes
The other side of Prop 19 is considerably less generous than the rules it replaced, and it affects anyone inheriting property from a parent. Before Prop 19, children could inherit a parent's home and keep the parent's low assessed value regardless of what they did with the property afterward, whether they moved in, rented it out, or sold it. That blanket protection is gone.
Under current rules, the parent-child exclusion only applies if the heir moves into the inherited home as their principal residence within one year of the transfer and files for the homeowners' exemption. Even then, the exclusion only covers the first $1,044,586 of value above the parent's assessed value, a cap that applies to transfers occurring between February 2025 and February 2027 and that the state adjusts every two years based on statewide home price growth. Anything above that cap gets partially reassessed, meaning the excess amount is added to the parent's original basis to set the new taxable value.
Rental properties, vacation homes, and any inherited property the heir doesn't move into as a primary residence get no exclusion at all. Those properties are reassessed to full current market value the moment title transfers, which can mean a dramatic jump in the annual tax bill compared to what the parent was paying, sometimes overnight.
Why this matters for San Diego families specifically
San Diego has no shortage of homes owned by the same family for decades, particularly in older coastal and central neighborhoods where assessed values have fallen far behind current market prices. For those families, the gap between a parent's assessed value and today's market value can be enormous, which makes the $1,044,586 exclusion cap and the one-year move-in requirement genuinely consequential rather than a technicality. A home that would have passed to the next generation tax-basis-intact under the old rules can now trigger a significant reassessment if the heir doesn't move in fast enough, or if the home's appreciation has outpaced the exclusion cap.
What this means if you're downsizing
If you're 55 or older and thinking about selling a long-held San Diego home for something smaller, Prop 19 may be the single biggest factor in whether that move makes financial sense. Run the numbers on your transferred basis before you list, factor in whether the replacement home's price will add anything to that base, and confirm the filing timeline with a tax professional so you don't miss the window for retroactive relief.
What this means if you're planning to leave property to your kids
If you're hoping to pass a long-held home to your children, the one-year occupancy requirement is the detail most families miss. If your heirs don't plan to move into the home as their primary residence within a year of inheriting it, whether because they already own a home or plan to rent the property out, they should expect a reassessment on whatever value exceeds the current exclusion cap. This is worth discussing as part of broader estate planning well before it becomes an active issue, since the difference between planning ahead and reacting after the fact can be a meaningfully different tax bill for your heirs.
Figuring out what Prop 19 means for your situation
Whether you're weighing a downsizing move or thinking about how a long-held property will pass to the next generation, the numbers are specific to your assessed value, your timeline, and current exclusion caps that shift every two years. If you want help running the math on a transfer or an inherited property, reach out and we'll walk through what Prop 19 actually means for your specific situation.