The Advantage Has Flipped: What the Latest Housing Debrief Tells Us About Where the Market Stands
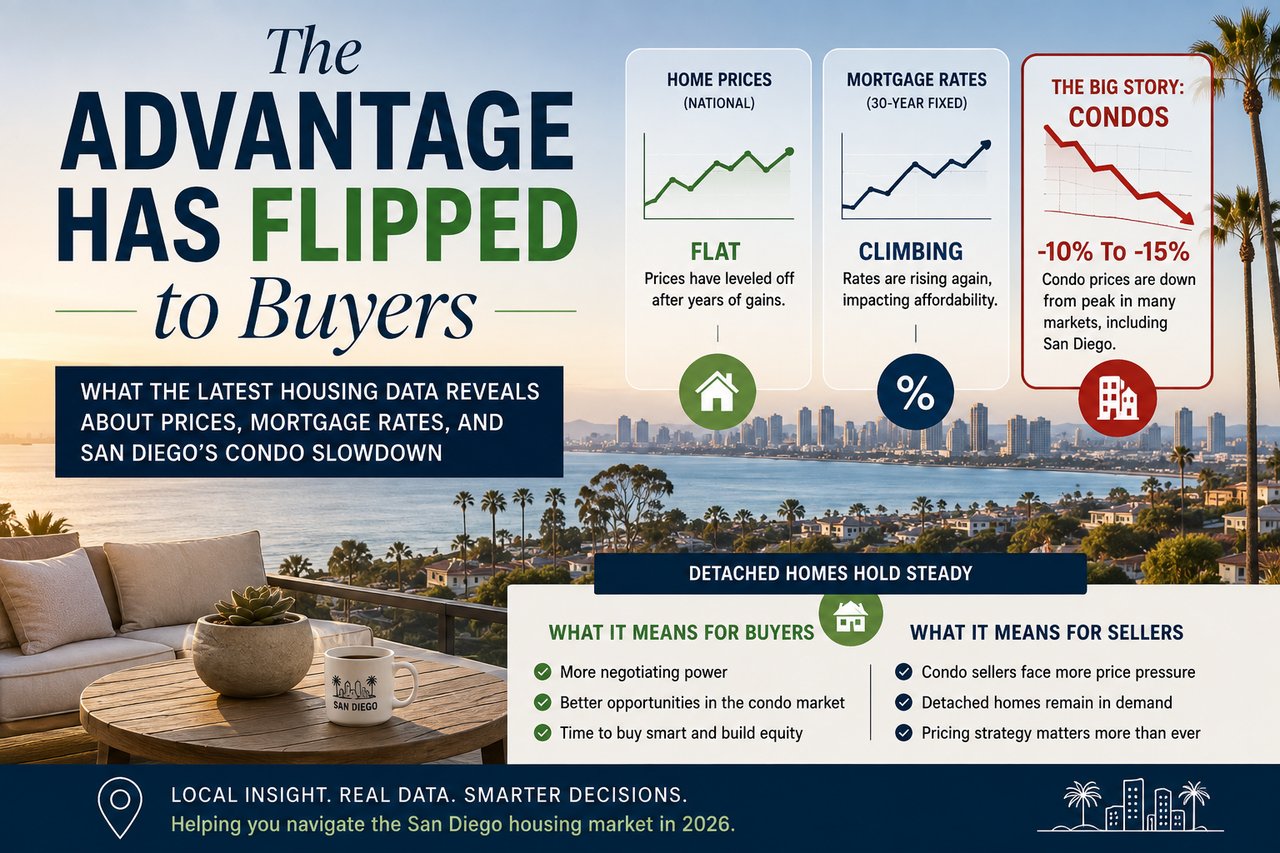
For most of the past several years, sellers held the upper hand. Now the scale has tipped the other way. The latest Housing Debrief from Reports on Housing lays out a market that has settled into a slight buyer's advantage nationally, with price growth flattening, mortgage rates creeping back up, and the gap between detached homes and condos widening into one of the more interesting stories in real estate right now. None of this points to a crash. It points to a market that has quietly rebalanced, and buyers who know how to read the data are in a much stronger negotiating position than they were even a year ago.
The scales have tipped toward buyers
Picture a real estate sign with buyers on one side and sellers on the other. For a long stretch after the pandemic, that sign would have read firmly in sellers' favor. Today it reads differently: a slight buyer's market, where negotiations favor buyers rather than sellers. That doesn't mean sellers have lost all leverage or that homes are sitting unsold everywhere. It means the tools buyers use to negotiate, price reductions, seller credits, and more flexible terms, are back on the table in a way they weren't during the frenzy years.
That shift shows up most clearly in what sellers are willing to offer just to get a deal done. Price reductions are more common. Sellers are more willing to cover closing costs or buy down a buyer's interest rate. Terms that would have been laughed off the table in 2021 and 2022, like extended contingency periods or repair credits, are back in the conversation. None of this happened overnight. It's the cumulative effect of higher rates and slower price growth wearing down sellers' pricing power month after month.
What home prices are actually doing
The Zillow Home Value Index tells the story in numbers. Nationally, home prices are up just 0.8 percent year over year and actually slipped 0.1 percent month over month in the most recent reading. That's a market that has essentially gone flat after years of sharp appreciation, which itself is a meaningful data point. Flat isn't falling apart. It's a market finding its footing after an unusually volatile few years.
Break that national number apart by property type and the picture gets more interesting. Detached single family homes are up 1.0 percent year over year, still positive, though also down 0.1 percent for the month. Attached homes, meaning condos and townhomes, are down 0.8 percent year over year and down 0.2 percent month over month. That's a real divergence. Detached housing is holding value, even if growth has slowed to a crawl. Attached housing is actually losing value on a year over year basis, and the monthly trend for condos is deteriorating faster than for houses.
This split isn't unique to any one metro area. It's showing up in the national numbers, and it's a preview of the deeper story playing out at the local level, which we'll get to in a moment.
Mortgage rates are creeping back up
Rates have been anything but stable since 2023, swinging between roughly 6 percent and 8 percent on the 30 year fixed according to Mortgage News Daily. Every time rates approached that 6 percent floor, buyers rushed back into the market, only to see rates climb again and cool things back off. That pattern has repeated itself several times over the past three years, and it's happening again now.
Rates touched close to that 6 percent floor earlier this year before turning higher, and the most recent reading has them back up around 6.67 percent. That uptick matters because it directly affects what buyers can afford to offer, and it helps explain why price growth has stalled even as rates remain well below their recent highs. Buyers aren't disappearing from the market, but every basis point increase in rate shaves a little more off what they're willing or able to pay, and that shows up in the flattening price data.
Why this isn't a crash, even though it doesn't feel great
Whenever price growth slows or a segment of the market starts losing value, the word "crash" starts getting thrown around. The Housing Debrief pushes back on that framing with a simple but useful mental model: a housing crash requires three ingredients to exist together at the same time. First, excessive oversupply, meaning far too many homes for sale relative to buyers. Second, genuinely low demand, not just softer demand, but a real drop off in buyers showing up. Third, sellers who have no choice but to sell, whether because of job loss, divorce, or financial pressure, and who will take whatever price they can get just to get out.
All three of those conditions have to line up simultaneously for prices to truly collapse the way they did in 2008. Right now, that alignment isn't happening. Inventory has grown in pockets, and buyer demand has cooled from the frenzy years, but the third ingredient, a flood of distressed, must sell sellers, simply isn't present in this market. Most sellers today have substantial equity, low fixed rate mortgages they're reluctant to give up, and no urgent financial reason to dump a home at any price. That's a fundamentally different setup than the last housing bust, and it's why a slowdown in price growth, or even outright price declines in a specific segment like condos, doesn't automatically translate into a crash for the broader market.
That distinction matters for how buyers and sellers should actually behave. A buyer's market with negotiating room is a very different environment to operate in than a market in free fall, even though headlines often blur the two together.
San Diego's condo conundrum
Nowhere is the detached versus attached divergence clearer than in San Diego County, where the August housing report dug into what's being called the condo conundrum. The headline finding: the attached home market, meaning condominiums and townhomes, is substantially slower than the detached home market, and that slower pace is what's pushing condo prices lower.
The numbers back it up. According to Zillow's Home Value Index, the median detached home in San Diego County was $1,009,454 as of June. The median attached home was $630,171, a genuinely more affordable entry point on paper. But affordability on the sticker price doesn't tell the whole story. The San Diego County median monthly HOA due for attached sales in June was $435. For detached homes, it was zero. That monthly carrying cost changes the math on what a condo actually costs to own every month, even when the purchase price looks like a bargain next to a house.
Then there's the speed of the market itself. Attached homes are taking an expected 122 days to sell in San Diego County, compared to 96 days for detached homes. That's not a small gap. A condo sitting on the market nearly a month longer than a comparable house gives buyers more room to negotiate, more time to compare listings, and less pressure to act fast, all of which drags on price.
The report frames this shift with a familiar analogy. Condominiums and townhomes used to function like the dollar menu at a fast food restaurant, an affordable, no frills way to get in the door. They offered a lower cost alternative to detached homes and served as a stepping stone to homeownership, often bundled with amenities like pools, spas, fitness centers, and clubhouses that made them feel like a good value. But just as the dollar menu quietly became the "value menu," with a family of four now paying around $25 for what used to be a genuinely cheap meal, the cost of owning a condo has climbed in ways that aren't always obvious from the listing price alone. Rising HOA dues, insurance costs, and the slower pace of sales have chipped away at what used to be a clear financial break for buyers trying to break into the market.
None of this means condos are a bad option. At $630,171 versus over $1 million for a detached home, the price gap is still enormous, and for many buyers a condo remains the only realistic path into San Diego County homeownership. But it does mean buyers and sellers need to go in with clear eyes about what's driving that price gap and why it's likely to persist as long as attached homes keep taking noticeably longer to sell than houses.
What this means if you're selling
If you're selling a detached home right now, you're operating in a market that's flat but not falling, with prices still slightly positive year over year. That said, the days of listing high and waiting for a bidding war are largely over in most areas. Buyers have leverage again, and pricing realistically from the start, rather than testing the market with an aspirational number, is more likely to get you to closing without months of sitting and price cuts along the way.
If you're selling a condo or townhome, especially in a market like San Diego, the calculation is tougher. With attached homes taking roughly a month longer to sell than detached homes and prices actually down year over year, expect buyers to negotiate harder and to factor HOA dues directly into their offer. Being upfront about the association's financial health, reserve funds, and dues history can help move a listing faster than hoping the right buyer overlooks those costs.
What this means if you're buying
Buyers are in the strongest negotiating position they've had in years. Price reductions, seller credits, and flexible terms are realistic asks again, not wishful thinking. That's especially true in the condo and townhome segment, where slower sales and softer prices are giving buyers real room to negotiate on price or ask for concessions that offset HOA costs.
The one thing working against buyers is the rate environment. With 30 year fixed rates back up around 6.67 percent after dipping closer to 6 percent earlier in the year, it's worth locking in terms and shopping rate options carefully rather than assuming today's rate is where things will stay. Timing the exact bottom of the rate cycle is nearly impossible, but understanding that rates have moved in a wide band for three straight years should inform how you think about affordability and whether to buy now or wait for the next dip.
The bottom line
The market hasn't crashed, and the data doesn't suggest one is coming, but it has clearly shifted. Detached homes are holding value while attached homes are losing ground, mortgage rates are ticking back up after a brief dip, and buyers across the board have more negotiating power than they've had in a long time. Whether you're weighing a purchase or thinking about listing, understanding which side of that divide your property or your target home falls on will shape how the next few months play out. If you want help reading the local numbers for your specific situation, reach out and we'll walk through what the data means for you.