The Home Sale Tax Break That Hasn't Moved Since 1997, and Why It Matters More in San Diego Than Almost Anywhere
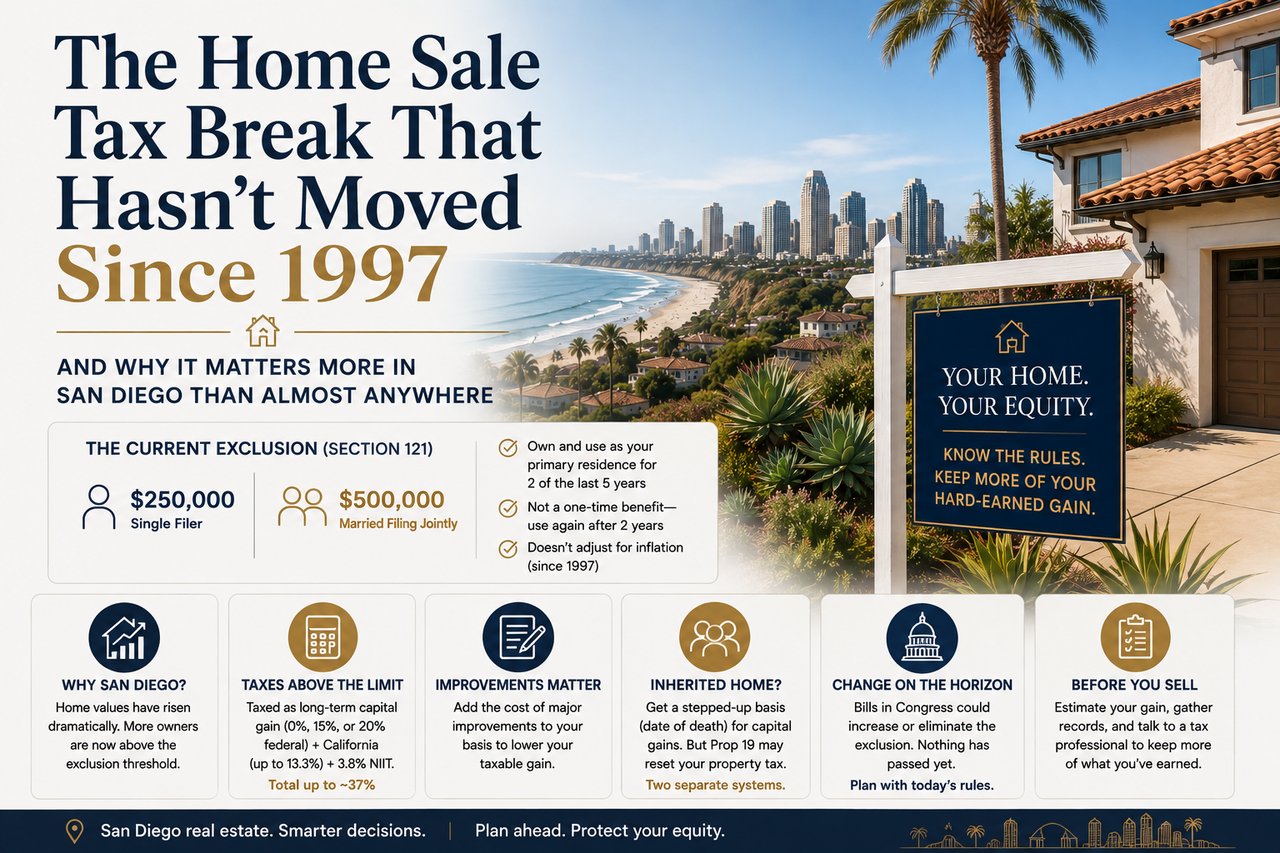
The federal tax exclusion on profit from selling your home has stayed at $250,000 for a single filer and $500,000 for a married couple since it was written into law in 1997, with no adjustment for inflation in nearly three decades. That's suddenly relevant again. Trump administration officials floated cutting or eliminating capital gains tax on home sales entirely as recently as August 2026, and two bills are sitting in Congress right now that would change these numbers for the first time in a generation. Nothing has passed yet, so the rules below are still exactly what applies today, but San Diego has more homeowners sitting close to, or well past, this threshold than almost anywhere else in the country, which makes this worth understanding before you assume a sale is tax free.
How the exclusion actually works
Section 121 of the tax code lets you exclude up to $250,000 of gain if you're single, or $500,000 if you're married filing jointly, from federal income tax when you sell your primary residence. To qualify, you need to have owned the home and lived in it as your primary residence for at least two of the five years before the sale. Those two years don't need to be continuous, and they don't need to be the most recent two years either, which gives some flexibility if you moved out for a period and rented the home before selling. This isn't a use-it-once benefit tied to your lifetime either; you can claim it again on a future home sale as long as you meet the ownership and use test each time and haven't claimed the exclusion on another home sale within the prior two years.
How your actual gain gets calculated
Your taxable gain isn't your sale price, it's your sale price minus your selling costs and your adjusted cost basis. Cost basis starts with what you originally paid for the home and grows with the cost of capital improvements you've made over the years, things like a kitchen remodel, a new roof, an addition, or major system replacements. Routine maintenance and repairs don't count, but real improvements do, and they directly reduce your taxable gain dollar for dollar. This is exactly why keeping records matters more the longer you own a home. A homeowner who bought in the 1990s and made $150,000 worth of documented improvements over three decades has a materially different tax bill than a neighbor with an identical sale price and no records to show for similar work.
Why San Diego owners are the ones who actually hit this ceiling
This exclusion was written when median home prices nationally were a small fraction of what they are now, and San Diego appreciation has outpaced most of the country over the past two and three decades. Consider a homeowner who bought a home in Carmel Valley or coastal North County in the late 1990s or early 2000s for $350,000 and sells it today for $1.4 million. Even after subtracting selling costs and a reasonable allowance for capital improvements, that's a gain well north of $900,000, comfortably clearing the $500,000 married exclusion with hundreds of thousands of dollars left exposed to tax. This is exactly the same population of owners who show up throughout content on Prop 13, since a rock bottom property tax basis and a large embedded capital gain tend to travel together. The lower your property tax bill has stayed over the years, the more likely your home has appreciated well past what the 1997 exclusion was ever designed to shelter.
What happens to the gain above the exclusion
Any gain above your exclusion amount gets taxed as a long-term capital gain if you've owned the home more than a year, at federal rates of 0, 15, or 20 percent depending on your income. California adds its own layer on top, and it's a meaningful one: California taxes capital gains as ordinary income, with no special discounted rate for long-term gains, at rates running from 1 percent up to 13.3 percent, that top rate including a 1 percent surcharge on income over $1 million. High earners can also owe an additional 3.8 percent Net Investment Income Tax on top of the federal capital gains rate. Stack all of that together and the maximum combined federal and California rate on a large home sale gain can run as high as roughly 37 percent on the portion above your exclusion. For a seller sitting on a $900,000 gain against a $500,000 exclusion, that's real money, not a rounding error.
The partial exclusion most people don't know about
If you're selling before meeting the full two-year ownership and use requirement, you're not necessarily out of luck. The IRS allows a reduced, prorated exclusion when the sale is primarily driven by a qualifying reason, a job change, a health issue, or another unforeseen circumstance the IRS recognizes. The math generally scales your exclusion based on the shortest of the time periods involved, so someone who lived in a home for one year of a required two before an unavoidable move might still shelter roughly half the full exclusion amount rather than none of it. It's worth raising with a tax professional before assuming an early sale forfeits this benefit entirely.
Inherited homes are a completely different system, and people mix the two up constantly
This is the point of confusion I run into most, because inherited property involves two separate tax systems that have nothing to do with each other, and conflating them leads people to badly misjudge what they'll actually owe. On the capital gains side, when you inherit a home, you get a stepped up cost basis equal to the property's fair market value on the date of death, a federal rule under IRC 1014. That step up wipes out essentially all of the capital gain that built up while your parents or whoever you inherited from owned the home. Sell shortly after inheriting, and you'll typically owe little to no capital gains tax even if the original owner paid a fraction of today's value decades ago.
Property tax is a completely separate question, governed by Prop 19, not the step up basis rule. Prop 19 eliminated the old parent-child exclusion for most inherited homes as of February 2021. If you inherit a home and don't move into it as your primary residence within one year, the county reassesses it to current market value for property tax purposes, full stop. Even if you do move in, the reassessment protection is capped, and for transfers occurring between February 16, 2025 and February 15, 2027, that cap sits at $1,044,586 above the parent's factored base year value. Miss the move in deadline, or exceed the cap, and your property tax bill resets to reflect today's value regardless of what happens with your capital gains basis. These are genuinely two different questions with two different answers, and it's worth getting both right rather than assuming a favorable answer on one tells you anything about the other.
What might actually change
The reason this topic is worth revisiting now rather than treating as settled is that real momentum exists behind changing it. The bipartisan More Homes on the Market Act, introduced in 2025, would double both exclusion amounts to $500,000 for single filers and $1 million for married couples, and index them to inflation going forward so this doesn't freeze again for another three decades. A separate bill, H.R. 4327, would eliminate the exclusion ceiling entirely. And the Trump administration has publicly floated the idea of cutting or eliminating capital gains tax on home sales altogether as of August 2026. None of this has become law as of now, and current sellers should plan around today's rules, not a proposal that may or may not pass. But if you're a long-time owner weighing the timing of a sale, it's worth knowing this is an active conversation in Washington rather than settled policy from 1997 that nobody's looking at anymore.
What this means if you're selling a long-held home
Pull together records of every capital improvement you can document before you list, since each one reduces your taxable gain directly, and decades of forgotten receipts add up to real tax savings. Run an actual estimate of your gain against your specific exclusion amount before you assume the sale is tax free, especially if you've owned the home more than fifteen or twenty years in an appreciating San Diego neighborhood. And if the number comes back meaningfully above your exclusion, talk to a tax professional about the current legislative landscape and your specific timeline rather than either panicking or assuming nothing can be done.
What this means if you inherited a family home
Get a professional appraisal or documented valuation as close to the date of death as possible, since that figure becomes your new cost basis and is the single most important number for minimizing capital gains tax on an eventual sale. Separately, and regardless of what that basis looks like, check the one-year move-in deadline and the current Prop 19 exclusion cap if you're hoping to keep anything resembling the original property tax basis. Treat these as two separate homework assignments, because they are.
The bottom line
A tax break that hasn't moved since 1997 was never built for today's San Diego prices, and a lot of long-time owners are going to find out the hard way that their gain is bigger than their exclusion. Whether that changes depends on legislation that's still sitting in Congress, not something you can count on before you sell. If you want help estimating your actual gain against your exclusion, sorting out capital improvement records, or untangling inherited property basis from Prop 19 property tax questions, reach out and we'll go through the numbers together.