Why San Diego Condos Are Losing Value While Single Family Homes Hold Steady
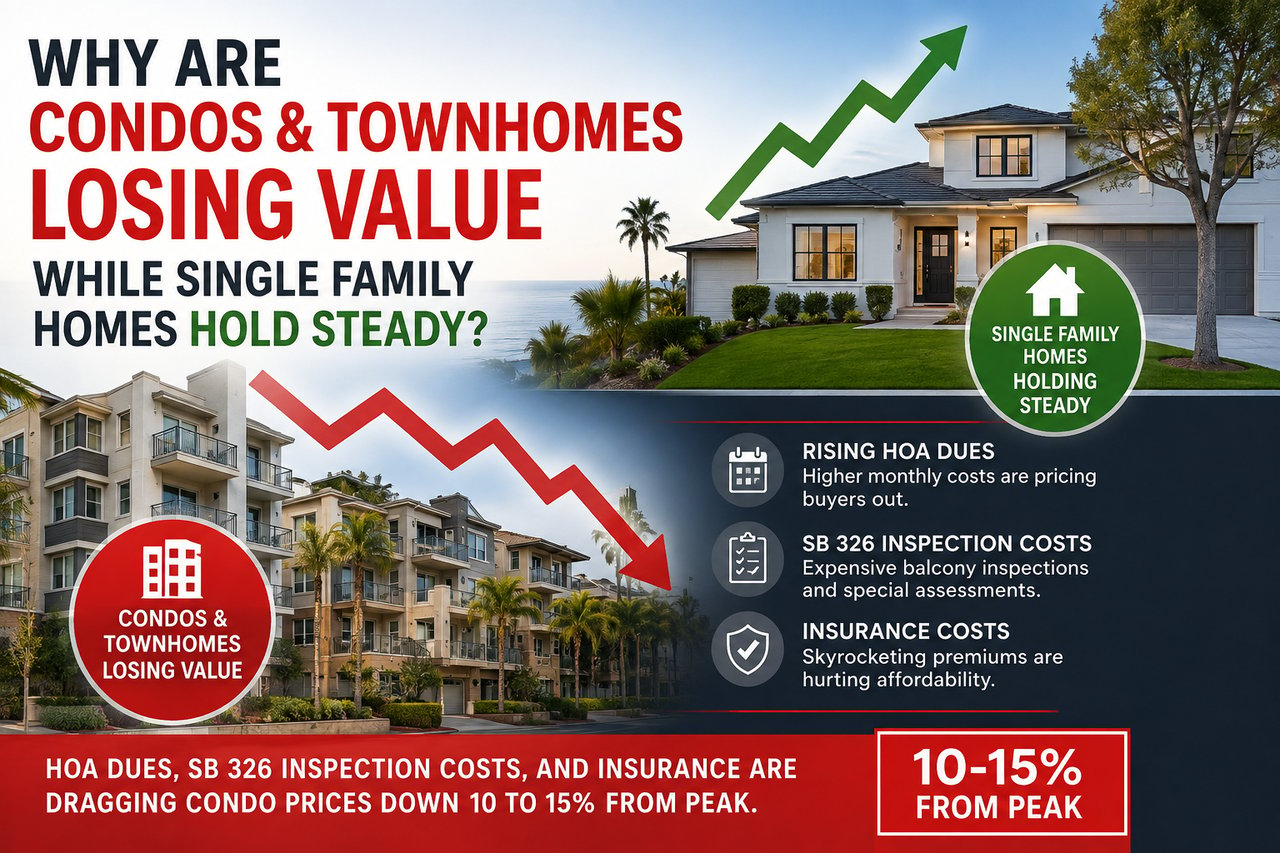
San Diego's housing market has split into two very different stories this year. Detached single family homes are holding close to their 2022 peak, with the countywide median at $1,074,000 in April 2026, up 5.8 percent from a year earlier. Attached condos and townhomes are moving in the opposite direction. The median for attached properties sat at $675,000 in May 2026, down 1.5 percent year over year, and older units in HOA communities have fallen 10 to 15 percent or more from their 2022 highs.
The gap isn't really about location or square footage. It comes down to three costs that buyers are now pricing into every offer on an older condo: HOA dues, mandatory balcony inspections, and insurance.
The numbers behind the divergence
The split shows up clearly in inventory and time on market. Detached home inventory has actually fallen 24.7 percent year over year, keeping that segment tight and competitive. Attached inventory has moved the opposite direction, up 5.6 percent year over year, giving condo buyers far more to choose from and far less urgency to act.
That shows up in how long homes sit. Detached homes are averaging 44 days on market, up 10 percent year over year, while attached properties average 38 days, up 24.4 percent year over year. Downtown San Diego condos specifically are running even slower, with some listings taking 70 to 90 or more days to sell. When a property type has more supply, less demand, and slower turnover all at once, prices soften, and that is exactly what's happening to older condos and townhomes right now.
HOA dues are climbing fast
The median monthly HOA fee in San Diego rose to $367 in 2025, up from $340 in 2024, and the share of listings carrying HOA dues climbed to roughly 57 percent, up from about 55 percent the year before. Downtown condos routinely run past $1,000 a month once amenities, staffing, and reserve contributions are factored in.
Insurance is the single biggest driver of these increases. Associations near canyons or coastal cliffs are seeing insurance renewals spike 15 to 30 percent annually as wildfire and flood risk push premiums higher, and boards are passing those increases straight through to owners in the form of higher monthly dues. California law lets HOAs raise dues up to 20 percent a year without a membership vote, so boards have a lot of room to keep passing rising costs along without much friction.
SB 326 is forcing expensive repairs into the open
Senate Bill 326, signed in 2019, requires every California condo association with three or more units to inspect exterior elevated elements, meaning balconies, decks, walkways, and stairways six feet or more off the ground that rely on wood framing for support. The first inspection deadline was January 1, 2025, and it has already passed. Associations now have to repeat these inspections every nine years going forward, and cities including San Diego are ramping up enforcement, with penalties reaching $500 a day for buildings that skipped the deadline.
The inspection itself isn't the expensive part. A typical report runs $5,000 to $20,000 depending on building size, and larger complexes can see inspection costs of $50,000 or more. The real financial shock comes after the inspection, when problems are found. Repairs to a single balcony can run $10,000 to $25,000, and when inspections uncover broader structural issues, associations have levied special assessments of $40,000 to $175,000 per unit to cover the work. For an older building with dozens of units needing repair, that adds up to a multimillion dollar bill split among the owners, and it's exactly the kind of unpredictable cost buyers are now trying to price around.
Insurance is getting harder and pricier to keep
Layered on top of HOA dues and SB 326 costs is a broader insurance market that's tightening across California. The state's one-year moratorium on wildfire-related non-renewals expired in January 2026, and insurers have moved quickly since then, in some cases using satellite and aerial imagery of roofs and yards to decide whether to renew a policy at all, sometimes without giving a clear reason. Insurers non-renewed more than 2.8 million homeowners policies statewide between 2020 and 2025 in fire-prone zip codes, and California's FAIR Plan, the insurer of last resort for properties that can't get standard coverage, is raising rates by 29.1 percent starting in October 2026.
Most of San Diego's coastal and urban core neighborhoods still have a functioning standard insurance market, so the issue there is rising price rather than an inability to get covered at all. But for HOAs anywhere near fire-exposed canyons or hillsides, the combination of higher premiums and shrinking carrier options is adding yet another line item that trickles down into monthly dues.
What this means if you're selling
If you own an older condo or townhome in an HOA community, expect buyers to ask pointed questions about reserve funds, recent or pending SB 326 inspection reports, and how much dues have risen over the past few years. A clean inspection report, a fully funded reserve account, and a stable insurance history are becoming real selling points, not just paperwork to hand over at closing. Given that attached inventory is up and days on market are stretching toward 40, sometimes far longer downtown, pricing realistically for these added carrying costs is likely to move a listing faster than holding out for pre-2023 comps.
What this means if you're buying
The softness in the condo market can work in your favor, but only if you do the homework first. Ask for the HOA's most recent SB 326 inspection report, the current reserve study, the insurance renewal history, and whether any special assessments are pending or already approved. A lower purchase price on an older unit can still turn into a bad deal if a $40,000 or larger assessment is waiting in the wings, or if the building's insurance is at risk of non-renewal.
Single family homes aren't facing these same structural cost pressures, which is a big part of why they've held their value while attached housing has softened, with detached inventory actually shrinking even as condo inventory grows. For now, the two-track market looks set to continue: houses holding steady on tight supply, and condos trading based on how well their HOA has kept up with dues, inspections, and insurance.
Thinking about buying or selling a San Diego condo
Whether you're weighing an offer on an older unit or trying to price a listing in this shifting market, the HOA's financials tell you more than the comps do. If you'd like help pulling an association's reserve study, SB 326 status, and insurance history before you make a move, reach out and we'll walk through it together.